

Blogs
PW Consulting: Water Filtration Systems Market Valued at $15.6B in 2025, Projected 9.8% CAGR to $30B by 2032
By PW Consulting, 2026-09-07
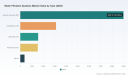
Navigating the Waters: Strategic Imperatives in the Global Filtration Landscape (2026–2032)
The global water filtration systems market stands at a critical inflection point. As we move through 2026, enterprises across residential, commercial, and industrial sectors face a convergence of regulatory pressure, technological innovation, and shifting consumer expectations. Our latest market research provides a comprehensive strategic roadmap for navigating this complex environment. This article outlines the key dynamics shaping the industry and explains why precise, data-driven intelligence is essential for competitive positioning over the next seven years.
RF Microwave Local Oscillator Board Market
Macro Growth Trajectory and Revenue Projections
Historical data from 2020 through 2025 demonstrates sustained momentum in the sector. The market has expanded from approximately 9.8 billion USD in 2020 to over 15.5 billion USD by 2025. This growth reflects more than mere population expansion; it signals a structural shift in how businesses and households value water quality, safety, and efficiency.
Carbon Nanotubes(CNT) Reactor Market
Looking forward, our forecasts project the market to reach approximately 17.5 billion USD in 2026, with continued expansion toward 30 billion USD by 2032. The compound annual growth rate across the forecast period is estimated at 9.8 percent. Such trajectory suggests that water filtration is transitioning from a discretionary upgrade to an operational necessity. For strategic planners, this implies that investment timing matters significantly. Early movers who align their product portfolios, supply chains, and channel strategies with these growth vectors will capture disproportionate market share. Late entrants may face saturated segments and elevated customer acquisition costs.
Twin-column Force Tester Market
Revenue contributions are not evenly distributed across segments. Our analysis reveals distinct regional and application-level shifts that require tailored go-to-market approaches. While comprehensive breakdown data is available in the full report, it is important to note that mature markets continue to anchor substantial volume, while emerging regions present higher growth elasticity. Similarly, residential applications dominate total revenue, yet commercial and industrial segments offer specialized margin opportunities that reward technical differentiation and long-term service contracts.
Competitive Landscape: Key Players and Strategic Moves
The market structure remains moderately fragmented, with the top three players holding roughly 25 percent combined share and the top five controlling approximately 35 percent. This concentration leaves ample room for niche specialists, regional champions, and well-capitalised entrants to compete on innovation, service quality, and brand trust.
Several established companies define the competitive baseline. A.O. Smith Corporation, headquartered in Milwaukee, Wisconsin, focuses on residential and commercial water treatment solutions, with particular emphasis on under-sink and whole-house purifiers. Pentair plc, based in London, UK, concentrates on advanced residential and commercial filtration systems, reverse osmosis platforms, and its Everpure branded portfolio for drinking and industrial applications. Brita LP, located in Oakland, California, specialises in pitcher-style and countertop filtration systems using advanced filter technology for point-of-use purification. GE Appliances, operating from Louisville, Kentucky, emphasises integrated refrigerator water filtration systems with in-house manufacturing of high-performance filters. Culligan International, based in Rosemont, Illinois, provides water softeners, filtration systems, and comprehensive residential and commercial treatment solutions. Kinetico Incorporated, headquartered in Pennsylvania, focuses on advanced whole-house filtration and softener systems using proprietary technology for residential and light commercial applications.
Recent corporate activities in early 2026 underscore the pace of competitive maneuvering. In January 2026, GE Appliances launched its first-ever in-house water filter manufacturing operation at Appliance Park, producing millions of high-quality refrigerator filters annually with full quality control. This move strengthens supply chain resiliency and directly combats counterfeit products under U.S. manufacturing initiatives. In February 2026, Waterdrop unveiled advanced tankless reverse osmosis and whole-house filtration solutions at the KBIS 2026 trade show in Las Vegas, signalling intensified product innovation in space-constrained and whole-home applications. In April 2026, Pentair released its 2025–2026 Residential Water Filtration product catalog featuring updated filtration systems, filters, and housings. Also in April 2026, iSpring showcased its WHO Series whole-house water filter system and WRO4000 Ultimate Whole House RO System at the WQA Convention & Expo 2026. Meanwhile, Graver Technologies exhibited advanced water filtration media and adsorbent solutions at the same event in Miami. These developments highlight parallel strategies: vertical integration, portfolio refresh, and trade-show-driven brand positioning.
Regulatory Dynamics and Certification Imperatives
Regulatory frameworks are rapidly reshaping demand patterns and product specifications. The Environmental Protection Agency has identified PFAS as a contaminant of concern in drinking water, driving demand for advanced filtration systems certified to reduce these so-called forever chemicals. This regulatory signal creates both compliance obligations and commercial opportunities for manufacturers who can substantiate performance claims with accredited testing.
Certification bodies are reinforcing quality benchmarks. The National Sanitation Foundation certifies point-of-use water filters for reduction in lead, chlorine, and microplastics under NSF/ANSI standards. These certifications have evolved from optional differentiators into baseline purchasing criteria for many commercial buyers and informed residential consumers. Additionally, WaterSense label eligibility requires point-of-use reverse osmosis systems to meet EPA efficiency and performance criteria for certified water filtration. Systems that fail to meet these efficiency thresholds may face exclusion from programs that influence procurement decisions in public-sector and sustainability-focused private contracts.
For strategic planners, the implication is clear: product development roadmaps must integrate regulatory tracking, third-party certification timelines, and claims-substantiation processes. Marketing communications that overstate performance without accredited evidence carry growing reputational and legal risk. Conversely, companies that proactively align R&D with emerging contaminant targets and efficiency benchmarks can convert compliance into competitive advantage.
Technological Shifts and Application-Level Demand Patterns
Technology segmentation continues to evolve as end-users balance removal performance, installation footprint, wastewater generation, and total cost of ownership. Reverse osmosis remains a dominant technology category, reflecting its broad contaminant-removal capability across residential and commercial use cases. Ultrafiltration and ultraviolet systems address specific pathogen and particulate challenges, often in applications where membrane-based removal or chemical disinfection is preferred. Activated carbon solutions continue to play a critical role in taste, odour, and chemical reduction, frequently serving as pre-treatment or point-of-use polish stages. Other emerging and specialised technologies address niche performance requirements and regional water-quality profiles.
Application-level demand patterns reveal divergent buying drivers. Residential purchases are increasingly influenced by health awareness, convenience, and aesthetic integration within kitchens and whole-home plumbing. Commercial buyers prioritise reliability, throughput, maintenance intervals, and serviceability, often evaluating filtration as part of broader facility management contracts. Industrial users focus on process protection, equipment longevity, and compliance with discharge or reuse standards, which can drive demand for customised configurations and high-durability media.
Recent product showcases reinforce these application-specific trends. Tankless reverse osmosis and whole-house filtration platforms are gaining visibility as installers and homeowners seek to reduce storage constraints and improve space utilisation. Whole-house systems are also attracting attention where comprehensive contaminant management and softener integration are valued. For manufacturers, the strategic question is not whether to participate in these segments, but how to configure product architecture, service ecosystems, and distribution partnerships to win repeated purchases and minimise churn.
Strategic Considerations for 2026 Decision-Makers
Enterprises evaluating their position in the water filtration systems market should consider several cross-cutting strategic questions. First, how should portfolio composition balance high-volume residential products with higher-margin commercial and industrial offerings? Second, where should manufacturing and sourcing be located to optimise cost, quality control, and resilience against counterfeit or supply disruption risks? Third, how should certification and claims-substantiation strategies be sequenced to support launch timing without compromising credibility? Fourth, which channel partners and trade presence strategies will most effectively reach specification writers, facility operators, and informed homeowners?
The answers to these questions depend on precise market sizing, segment-level growth rates, regional demand intensity, and competitive share dynamics. General directional insight is useful for framing, but executive decisions require granular intelligence. For example, understanding which applications are expanding fastest in specific regions can inform capacity allocation and sales-force deployment. Knowing how certification prerequisites differ across product types can shape R&D staging and regulatory affairs budgets. Recognising where concentration is rising or easing can guide merger, acquisition, and partnership strategies.
What Our Market Research Delivers
Our full Water Filtration Systems Market study is designed to support these decisions with operational depth. The report integrates historical performance data from 2020 through 2025 with a detailed forecast extending to 2032. It examines market size progression in absolute revenue terms and provides compound growth analysis across the forecast horizon. Beyond headline figures, the study breaks down demand across region, type, and application dimensions, enabling readers to identify where growth is concentrated and where competition is intensifying.
The competitive analysis section profiles leading companies, their headquarters, product focus, and recent strategic developments. It connects corporate announcements and trade-show activity to broader positioning themes, helping readers interpret whether rivals are pursuing scale, differentiation, vertical integration, or portfolio extension. The regulatory and dynamics section maps current contaminant concerns, certification requirements, and efficiency standards to practical implications for product design, marketing claims, and procurement eligibility. Together, these components create a decision-ready framework rather than a static data dump.
Readers will also find segmentation insights that clarify how revenue is distributed among major technology categories and application segments. The report addresses market concentration indicators, which help assess the room available for new entrants and the degree of pricing power likely to persist. By combining quantitative sizing with qualitative dynamics, the study supports scenario planning, channel strategy, and investment prioritisation.
Why This Intelligence Matters Now
The 9.8 percent compound growth trajectory and the projected expansion toward 30 billion USD by 2032 indicate that water filtration will remain an attractive but increasingly contested arena. Regulatory pressure on contaminants such as PFAS, lead, chlorine, and microplastics is raising the performance floor. Certification and efficiency labels are influencing purchasing decisions in both public and private markets. Supply chain resiliency and counterfeit mitigation are becoming integral to manufacturing strategy, as demonstrated by recent in-house production initiatives. At the same time, rapid product unveilings and catalog updates signal that feature competition is accelerating, particularly in tankless, whole-house, and point-of-use categories.
In this environment, ambiguity is costly. Companies that rely on extrapolations or fragmented sources risk misallocating resources, launching products that miss certification windows, or entering regions where demand intensity does not justify fixed costs. A rigorous, updated market study reduces that uncertainty by consolidating historical data, forward estimates, competitive movement, and regulatory context into a single analytical structure.
Accessing the Full Strategic Picture
This article provides a high-level orientation to the forces shaping the water filtration systems market in 2026 and beyond. It is intended to demonstrate the depth and relevance of our research while preserving the detailed segmentation data, region-level analysis, application splits, and company-specific intelligence for the complete report. Those granular insights are essential for translating market direction into concrete actions such as capacity planning, product launch sequencing, certification investment, channel selection, and territory prioritisation.
For executives, commercial leaders, and strategy teams who need to move from awareness to execution, the full study offers the precision required to make confident decisions. We invite you to access the complete report to explore the underlying market size progression, segment dynamics, concentration metrics, and competitive profiles in detail. In a market expanding steadily toward 2032, the organisations that act on accurate, current intelligence will be best positioned to capture sustained value.
For detailed analysis of this topic, please visit the official page: Water Filtration Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RTA Furniture Market to Hit $18.74B in 2025, Growing 8.26% CAGR to $32.66B by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Ready-to-Assemble Furniture Market: Navigating Growth and Disruption in 2026
Executive Summary
The Ready-to-Assemble (RTA) furniture sector stands at a pivotal inflection point entering 2026. As consumer preferences shift toward flexible living solutions, sustainable materials, and cost-effective home furnishing, the market is experiencing robust expansion driven by both residential demand and commercial adaptation. This industry insight outlines the strategic landscape of the RTA furniture market, synthesizing historical performance, forward-looking projections, and competitive dynamics to inform executive decision-making. The analysis below draws upon comprehensive data tracking from 2020 through the forecast horizon extending to 2032, offering a calibrated view of where value creation is concentrated and where operational risks require mitigation.
Worldwide Prevailing Torque Nuts Market
Market participants navigating this environment must reconcile accelerating revenue growth with structural pressures including regulatory compliance, supply chain reconfiguration, and intensifying competition from both legacy manufacturers and digital-native retailers. The following sections unpack the macro trajectory, segmentation currents, competitive positioning, and the operational intelligence embedded in our latest research publication.
Worldwide Gas Cylinder Scale Market
Market Trajectory and Growth Architecture
Historical Resilience and Accelerated Expansion
Over the past five years, the RTA furniture market has demonstrated consistent upward momentum, with total revenue climbing from approximately 10.75 billion USD in 2020 to 18.74 billion USD in 2025. This progression reflects a compound growth trajectory that has outstripped many adjacent home goods categories, underpinned by the sector's inherent advantages in logistics efficiency, storage density, and price accessibility. The transition from fragmented regional demand to a more synchronized global consumption pattern has been a key enabler, as has the broader normalization of home-centric spending following earlier disruptions to retail and mobility patterns.
Upcycled Denim Product Market
Importantly, the growth profile is not merely a function of post-pandemic recovery effects. Underlying demand drivers now include sustained urbanization in emerging economies, the proliferation of small-space living configurations, and the integration of RTA formats into hybrid work environments. These factors have broadened the addressable base beyond traditional DIY enthusiasts to include property developers, co-working operators, and e-commerce platforms seeking streamlined fulfillment options.
Forecast Outlook Through 2032
Looking ahead, the market is projected to maintain a strong growth cadence, with annualized expansion reflecting a CAGR of approximately 8.26 percent across the forecast window from 2026 through 2032. Revenue is expected to progress from roughly 20.8 billion USD in 2026 toward over 32.6 billion USD by 2032. This trajectory signals a market that is maturing yet still capable of delivering double-digit incremental value in absolute terms, provided companies align product strategies, distribution capabilities, and compliance frameworks with evolving buyer expectations.
The forecast assumes continued penetration of online channels, incremental innovation in tool-free assembly and modular configurations, and steady investment in manufacturing capacity by both incumbent producers and new entrants targeting niche application segments. Strategic planners should treat these projections as a baseline scenario rather than a deterministic path; sensitivity to raw material costs, trade policy shifts, and consumer sentiment will require agile scenario modeling.
Structural Dynamics Shaping the Competitive Field
Concentration and Ecosystem Complexity
The competitive environment in RTA furniture is characterized by a meaningful degree of consolidation. The top three firms command a combined share of approximately 58.2 percent of total market revenue, while the top five players extend their collective footprint to roughly 65.4 percent. This concentration underscores the strategic importance of scale, brand recognition, and distribution reach, yet it also reveals pockets of opportunity for focused manufacturers and private-label retailers that can differentiate on design, speed-to-market, or specialized application expertise.
Beyond the headline concentration figures, the industry ecosystem includes a layered network of raw material suppliers, flat-pack assemblers, logistics intermediaries, and digital marketplaces. Companies that can orchestrate these touchpoints effectively gain leverage in pricing, customization, and fulfillment reliability. Conversely, fragmentation in upstream supply or reliance on single-source manufacturing hubs can expose firms to margin compression when demand patterns shift unexpectedly.
Regulatory and Compliance Pressures
Regulatory dynamics are increasingly shaping product design and sourcing strategies. A notable example occurred in early 2025, when RTA furniture manufacturers adjusted supply chains to comply with Minnesota's Amara Law, which bans intentionally added PFAS chemicals in upholstered products. This development illustrates a broader trend: environmental and health-related regulations are no longer confined to finished goods labeling but are influencing material selection, vendor qualification, and even regional sourcing decisions.
Compliance is becoming a competitive differentiator. Brands that proactively integrate chemical restrictions, recyclability considerations, and transparent sourcing into their design cycles are better positioned to win procurement contracts with regulated institutional buyers and to avoid costly retrofit cycles later. Strategic teams should treat regulatory horizons as input variables for product roadmaps, not as downstream legal checks.
Channel Evolution and E-commerce Integration
Distribution architectures continue to evolve as digital-native retailers expand their assortments and physical-to-digital hybrids gain traction. Large-format showrooms, click-and-collect services, and omnichannel delivery capabilities are increasingly table stakes, particularly for consumers who want to visualize scale, texture, and assembly complexity before purchase. At the same time, dropshipping and OEM partnerships enable smaller brands and regional retailers to access RTA inventory without owning manufacturing assets, lowering barriers to entry and intensifying competition at the assortment level.
The interaction between channel strategy and product design is particularly significant in this market. Flat-pack efficiencies that reduce shipping costs can be undermined if assembly friction rises or if returns increase due to mismatched expectations. Winning operators balance cost-efficient logistics with customer experience engineering, including clearer assembly instructions, modular repairability, and packaging that protects both margin and brand perception.
Segmentation Fluidity and Strategic Implications
Material and Type Considerations
The material composition of RTA offerings continues to evolve as manufacturers respond to cost structures, aesthetic trends, and application requirements. Wood-based products remain deeply embedded in the category, supported by their perceived durability and broad consumer familiarity, while glass, steel, and other material variants serve distinct functional and design niches. The strategic question for product leaders is not simply which material dominates in aggregate, but how material choices interact with target applications, shipping economics, and regional preference patterns.
For example, modular storage and entertainment units benefit from material combinations that balance load-bearing capacity with visual lightness, while dining and workspace sets must reconcile assembly simplicity with long-term structural integrity. Companies that invest in material innovation while preserving flat-pack efficiency can unlock higher perceived value without sacrificing logistics performance.
Application Patterns and Use-Case Expansion
Application demand is anchored by residential use, which accounts for the majority of revenue, but commercial and hybrid applications are gaining relevance. Home-based workspaces, furnished rentals, student housing, and small commercial interiors all generate demand for RTA products that combine rapid deployment with acceptable aesthetics. This diversification matters because application mix influences SKU breadth, packaging requirements, and service expectations. A product line optimized for household self-assembly may not align with procurement specifications for office interiors, where vendor-managed delivery and warranty terms can be decisive.
Strategic planning should therefore evaluate application segments as distinct value pools with their own buying committees, delivery expectations, and renewal cycles. Firms that treat the home and office segments as interchangeable risk under-serving the specific requirements that drive repeat procurement and referral.
Competitive Landscape: Leaders and Specialized Players
The RTA furniture market features a blend of large-scale manufacturers, global retail brands, and specialized flat-pack producers that serve e-commerce and OEM channels. Understanding the strategic posture of these participants provides context for partnership decisions, competitive benchmarking, and market entry planning.
Major Incumbents and Broad Portfolios
Several established players anchor the market through extensive product collections, multi-channel distribution, and strong brand recognition. Sauder Woodworking Co., headquartered in Archbold, Ohio, is recognized as North America's leading producer of ready-to-assemble furniture, with more than forty collections spanning entertainment, home office, bedroom, kitchen, and storage categories. Its scale and category breadth position it as one of the top five residential furniture manufacturers in the United States, enabling broad retailer relationships and consistent volume throughput.
Ashley Furniture Industries, based in Arcadia, Wisconsin, operates as one of the world's largest furniture manufacturers and maintains a dedicated RTA furniture line that includes casegoods, stationary and motion upholstery, mattresses, and complete RTA collections. With more than 1,125 U.S. stores and direct-to-consumer programs, Ashley combines manufacturing depth with extensive retail reach, allowing it to absorb demand fluctuations and test new formats across multiple channels.
IKEA, originating in Sweden with significant U.S. operations, remains a global leader in affordable flat-pack RTA furniture, offering extensive residential and office collections alongside click-and-collect services and store-based fulfillment. Its influence extends beyond product sales to shaping consumer expectations around self-assembly, modular expansion, and value-oriented design.
Specialized Manufacturers and Channel Enablers
Alongside broad-line incumbents, a set of specialized manufacturers and retail intermediaries plays an important role in expanding assortment diversity and supply flexibility. Bim Furniture, based in Poland with U.S. market presence, operates as a high-volume RTA flat-pack manufacturer specializing in entertainment units, dressers, and tables for e-commerce retailers, with dropshipping and OEM capabilities that reduce inventory risk for partners. Intermeble, also headquartered in Poland with U.S. presence, is a dedicated RTA flat-pack producer offering large production capacity for entertainment, storage, and dining furniture, giving retailers and brands additional sourcing leverage.
Dorel Industries, from Canada with U.S. market presence, is a major RTA furniture producer whose collections emphasize tool-free assembly and modular designs, distributed through direct-to-consumer and retail channels. Its design philosophy reflects a growing consumer preference for simplified assembly without sacrificing structural robustness. Wayfair, headquartered in the United States, operates as a major retailer offering extensive RTA furniture collections from multiple manufacturers, supported by omnichannel delivery and large-format showrooms. Its platform model aggregates supply from diverse producers, giving consumers breadth while exposing manufacturers to performance-based visibility and ranking dynamics.
Recent Market Activity and Sentiment Signals
Trade events continue to serve as barometers of competitive energy and sourcing momentum. In October 2024, the High Point Market fall edition featured four new Polish RTA furniture exhibitors, including Bim, joining the RTA segment alongside returning manufacturers. The participation of new sourcing partners at a major industry market signals continued appetite for capacity expansion, design differentiation, and cross-border supply relationships. Such developments often precede shifts in assortment availability, pricing dynamics, and retailer development calendars.
These activity patterns reinforce the notion that the market is not static. New entrants can quickly alter regional availability, while returning manufacturers refine their offerings in response to feedback from interior designers, retail buyers, and end consumers. Strategic monitoring of showroom introductions, partnership announcements, and capacity expansions can provide early warning of changing competitive intensity.
What the Report Delivers: Operational Intelligence for 2026 Decisions
Our latest RTA furniture market research is designed to convert macro trends into actionable planning inputs. The publication is structured to support strategy, commercial, and supply chain teams in evaluating opportunity, risk, and execution priorities. Key elements include:
- Forward-looking market sizing and trajectory analysis that connects historical performance with multi-year forecasts, enabling capacity planning and investment phasing.
- Segment-level context that clarifies how material types, application categories, and regional demand patterns interact without exposing every numerical split, preserving analytical depth while encouraging deeper review through the source platform.
- Competitive profiling of leading manufacturers, retailers, and specialized producers, including business model orientation, channel strategy, and recent activity signals relevant to partnership and risk assessment.
- Analysis of regulatory and compliance developments, including material restrictions and environmental requirements that can change sourcing feasibility and product design timelines.
- Guidance on channel strategy, covering the implications of omnichannel fulfillment, showroom experiences, dropshipping models, and OEM relationships for margin and service design.
- Strategic scenario considerations that help leadership teams stress-test assumptions around demand volatility, input cost movements, and competitive entry.
Each section is written to be directly usable in board-level discussions, annual planning cycles, and portfolio reviews. The intent is not simply to present data points, but to translate them into decision-ready frameworks that clarify where to commit resources, where to monitor leading indicators, and where to build flexibility.
Strategic Recommendations for Leadership Teams
As organizations prepare for 2026, several strategic priorities should shape their approach to the RTA furniture market:
First, align product development with application-level value rather than broad category assumptions. Residential demand remains the anchor, but workspace, furnished rentals, and hybrid interiors are creating differentiated requirements for durability, delivery, and warranty. Tailoring SKU architecture to these use cases can improve conversion and reduce returns.
Second, treat compliance and material transparency as design inputs rather than after-the-fact checks. Regulatory changes, such as restrictions on intentionally added chemicals in upholstered products, can affect supplier eligibility and reformulation timelines. Early integration reduces disruption and strengthens positioning with institutional buyers.
Third, evaluate channel partnerships with a clear view of fulfillment economics and customer experience. The efficiency of flat-pack logistics can be offset if assembly complexity, packaging fragility, or mismatched expectations drive returns. Brands and retailers that invest in instruction clarity, modular repair, and realistic product visualization typically perform better on repeat purchase and review quality.
Fourth, monitor competitive entry signals and sourcing diversification opportunities. The emergence of new exhibitors at major markets and the ongoing expansion of specialized manufacturers indicate that supply alternatives are evolving. Diversifying qualified sources can reduce concentration risk and support faster response to regional demand shifts.
Fifth, build scenario discipline into planning processes. Revenue growth looks robust on a base trajectory, but sensitivity to input costs, trade conditions, and consumer confidence should be reflected in capacity decisions, inventory posture, and promotional strategy. The companies that navigate this market well will be those that combine growth ambition with operational flexibility.
Conclusion: A Market Ready for Informed Strategic Action
The Ready-to-Assemble furniture market is entering 2026 with strong momentum, a concentrated yet still competitive structure, and a set of dynamics that reward companies capable of integrating design, compliance, channel strategy, and supply agility. Aggregate growth signals are compelling, but the real strategic value lies in understanding how that growth is distributed across applications, materials, channels, and competitive positions, and how leadership teams can respond before trends become commoditized.
This executive overview has outlined the macro direction, the structural forces shaping competition, and the types of operational intelligence available to support 2026 decision-making. For a complete view of segmentation context, forecast granularity, competitive profiles, and the supporting analytical framework, we invite stakeholders to access the full market research through our source platform. The detailed intelligence contained there is designed to support precise planning, risk calibration, and portfolio strategy across the forecast horizon to 2032.
For detailed analysis of this topic, please visit the official page: RTA (Ready-to-assemble) Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Methyl Orthoformate Market to Hit $152.5M by 2032, Driven by 5.4% CAGR
By PW Consulting, 2026-09-07
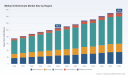
Strategic Intelligence for the Methyl Orthoformate Market: Navigating Growth and Complexity in 2026
The global chemical industry is undergoing a period of recalibration, where specialty intermediates play an increasingly critical role in the supply chains of essential downstream sectors. Among these, Methyl Orthoformate stands out as a high-value compound with expanding utility in agrochemicals, pharmaceuticals, and fine chemical synthesis. As we move through 2026, understanding the trajectory of this market is no longer optional for stakeholders aiming to secure competitive advantage. It requires a granular understanding of historical performance, production methodologies, regional shifts, and regulatory frameworks.
Worldwide Wastewater Aerator Market
In our newly released market research on Methyl Orthoformate, we provide a comprehensive analysis designed to equip decision-makers with the intelligence needed to navigate this evolving landscape. This report is not merely a collection of statistics; it is a strategic tool built to inform capacity planning, investment decisions, and supply chain optimization. By examining the period from 2020 through 2032, we offer a forward-looking perspective that highlights both the resilience and the dynamic nature of this sector. The following insights summarize the scope and strategic value of our findings, illustrating why this intelligence is vital for corporate strategy in 2026 and beyond.
Worldwide Near-Infrared Linear Polarizer Market
Market Trajectory and Scale: A Decade of Steady Expansion
The foundational narrative of the Methyl Orthoformate market is one of consistent growth. Our historical analysis covering the years 2020 to 2025 reveals a clear upward trend in global revenue, reflecting increasing demand across key application verticals. Starting from a valuation of approximately 75.4 million USD in 2020, the market expanded to reach 106.5 million USD by 2025. This trajectory sets the stage for the forecast period spanning 2026 to 2032, during which the market is projected to continue its ascent.
Worldwide Medical Oxygen Plant Market
Based on current indicators and planned capacity expansions, the market is expected to reach 110.91 million USD in 2026. The growth momentum is anticipated to persist through 2032, with projections suggesting a valuation of 152.5 million USD. This long-term expansion is underpinned by a compound annual growth rate (CAGR) of 5.4 percent over the forecast period. This rate indicates a stable yet robust environment, suggesting that demand drivers are structural rather than cyclical. For industry participants, this implies that investments made today in production capability or distribution networks are likely to yield returns over an extended horizon.
The consistency of this growth curve is particularly significant for stakeholders evaluating risk. While many chemical segments face volatility due to raw material price fluctuations or geopolitical tensions, Methyl Orthoformate exhibits a degree of stability supported by its critical role in specialty chemical formulations. The projected figures for the late 2020s, such as the expected reach of 141.29 million USD by 2030, provide a benchmark for long-term strategic planning. These numbers serve as a baseline for internal forecasting and help organizations align their resource allocation with market realities.
Production Methodologies and Technological Context
A critical component of understanding the Methyl Orthoformate market lies in examining the production technologies that drive supply. The dominant method for industrial-scale preparation involves the methanolysis of hydrogen cyanide. In this process, hydrogen cyanide reacts with three equivalents of methanol to produce Trimethyl Orthoformate. This chemical pathway is central to the supply dynamics of the market.
Our report delves deep into the implications of these production methods. The reliance on the hydrocyanic acid method highlights the importance of supply chain security for raw materials such as hydrogen cyanide and methanol. Fluctuations in the availability or pricing of these feedstocks can directly impact the cost structure and profitability of manufacturers. Furthermore, the synthesis mechanism underscores the need for stringent safety protocols and technical expertise, as handling hydrogen cyanide requires specialized infrastructure and compliance measures.
Another key aspect of the production landscape is the synthesis of Trimethyl Orthoformate, a primary variant of Methyl Orthoformate. This compound is typically characterized as a colorless transparent liquid with an ester odor, often requiring a minimum content purity of 99.0 percent for high-end applications. The quality specifications dictate the suitability of the product for sensitive applications in pharmaceuticals and advanced chemical synthesis. Manufacturers capable of consistently delivering high-purity grades are positioned to capture premium segments of the market, whereas those producing lower grades may find themselves relegated to bulk agrochemical intermediates.
The report analyzes how different production technologies influence market segmentation. Routes based on hydrocyanic acid continue to hold a significant share of the production capability, reflecting their established efficiency and scalability. However, alternative methods, such as those involving sodium metal, also contribute to the overall supply mix. The interplay between these methods, their respective cost profiles, and their environmental footprints is a key area of analysis in our study. Understanding these technological nuances allows procurement managers and supply chain strategists to assess supplier capabilities more accurately and negotiate terms with a clearer view of production constraints.
Application Landscape: Driving Forces and Sector Dynamics
The demand for Methyl Orthoformate is driven by its diverse applications, with certain sectors exerting a stronger pull on market growth than others. The report identifies key application segments that define the demand structure. The pesticides and agrochemicals sector represents a major driver of consumption. Methyl Orthoformate serves as a vital intermediate in the synthesis of various active ingredients and adjuvants used in crop protection. As global agricultural practices continue to evolve, with a focus on efficiency and yield optimization, the demand for high-quality intermediates in this sector remains resilient.
In parallel, the pharmaceuticals industry constitutes another significant application avenue. The compound is utilized in the synthesis of pharmaceutical intermediates, where purity and consistency are paramount. The growth of the pharmaceutical sector, particularly in regions with expanding healthcare infrastructure and increasing R&D investment, contributes to the steady demand for Methyl Orthoformate. The ability of manufacturers to meet the rigorous quality standards required by pharmaceutical clients is a differentiating factor in this segment. Companies that invest in quality control and certification are better positioned to capture value in this high-margin application area.
Beyond these primary drivers, there are additional applications including spices, dyes, and other fine chemical uses. While these segments may represent a smaller portion of the overall volume, they offer diversification opportunities for producers and users alike. The versatility of Methyl Orthoformate allows it to bridge multiple industries, providing a buffer against sector-specific downturns. For instance, a slowdown in agrochemical demand might be offset by growth in fine chemical synthesis, stabilizing the overall market for the compound. Our analysis explores these application dynamics in detail, highlighting how shifts in downstream industries ripple upstream to affect Methyl Orthoformate demand.
The interplay between these applications also influences pricing and product specifications. Agrochemical formulations may tolerate slightly different purity profiles compared to pharmaceutical intermediates, affecting manufacturer specialization strategies. Companies must therefore align their production capabilities with the specific requirements of their target markets. The report provides insights into how application trends are shaping the competitive landscape, helping organizations identify growth niches and potential disruption points within their value chains.
Regional Perspectives and Global Trade Flows
The geographic distribution of Methyl Orthoformate production and consumption reveals a complex web of regional dynamics. The Asia Pacific region stands out as a dominant hub in terms of market share and activity. This concentration is driven by a combination of factors, including the presence of major manufacturing centers, supportive industrial policies, and robust domestic demand from downstream chemical sectors. Within this region, specific countries have emerged as key players, hosting a significant number of producers and contributing substantially to global supply.
North America and Europe also represent important markets, characterized by different demand profiles and regulatory environments. In these regions, demand is often driven by specialized applications in pharmaceuticals and high-end agrochemicals. The market in these developed economies tends to prioritize quality, reliability, and compliance with stringent environmental and safety standards. As a result, supply chains in North America and Europe often rely on a mix of local production and imports from global suppliers who can meet these rigorous requirements.
Latin America and the Middle East and Africa, while smaller in terms of overall market volume, present growth opportunities and specific trade dynamics. For example, trade data indicates flows of Methyl Orthoformate from China to other regions, such as exports to Mexico. These trade connections highlight the global nature of the supply chain and the importance of logistics and export capabilities. Regulatory factors also play a role in shaping regional trade. For instance, the inclusion of certain producers in official catalogs related to green food additives can influence market access and perception in specific regions. Such regulatory developments create both opportunities and barriers, requiring stakeholders to monitor policy changes closely.
The report does not just list regional data points; it contextualizes them within broader geopolitical and economic trends. We examine how trade policies, transportation costs, and regional industrial strategies affect the flow of Methyl Orthoformate across borders. Understanding these regional nuances is essential for companies looking to expand their footprint or mitigate supply chain risks. For instance, reliance on a single region for supply can expose organizations to disruptions, making regional diversification a prudent strategy. Our analysis provides the context needed to evaluate these risks and opportunities effectively.
Competitive Landscape and Key Industry Players
The competitive environment in the Methyl Orthoformate market is defined by a mix of specialized manufacturers and integrated chemical producers. Market concentration metrics indicate that the top three companies hold a combined share of approximately 45.0 percent, while the top five companies account for around 55.0 percent. This level of concentration suggests a market where established players hold significant influence, yet there remains room for competitive differentiation through quality, capacity, and service.
Several key companies are profiled in detail within our report, offering insights into their capabilities and strategic positioning. Hebei Chengxin Co., Ltd., based in Shijiazhuang, Hebei, China, is recognized as a producer of Trimethyl Orthoformate. The company supplies products as a colorless transparent liquid with high purity content, catering to agrochemicals and pharmaceutical intermediates. Their packaging options, which include plastic or galvanized drums and ISO tanks, reflect a focus on flexible logistics solutions. Notably, Hebei Chengxin has been listed in the Chinese Ministry of Agriculture and Rural Affairs green food additives catalog, a regulatory distinction that underscores their compliance and potential market access advantages.
Linshu Huasheng Chemical Co., Ltd., located in Linshu County, Shandong, is another specialist manufacturer highlighted in the analysis. This high-tech enterprise is ISO 9001 and 14001 certified and boasts an annual capacity of 4,000 tons for Trimethyl Orthoformate. Their broader portfolio, which includes Triethyl Orthoformate and Phosphorous Acid, indicates a diversified approach to orthoester chemistry. Such capacity and certification levels position Linshu Huasheng as a significant supplier capable of meeting large-volume orders while adhering to quality and environmental management standards.
Fushun Shunte Chemical Co., Ltd., based in Fushun, Liaoning, stands out as a comprehensive producer of Trimethyl Orthoformate and related orthoformates. Their utilization of hydrocyanic acid resources aligns with the dominant production methodology, and their focus on fine chemicals as an exporter suggests a strategy oriented toward international markets. Similarly, Yingkou Cynovate Chemical Technology Co., Ltd., located in Yingkou, Liaoning, operates with a capacity of 2,500 tons per year for Trimethyl Orthoformate. Their production focus on related orthoformates for pharmaceutical and advanced chemical synthesis highlights the importance of specialized intermediates in high-value applications.
These profiles illustrate the diversity of strategies within the competitive landscape. Some companies emphasize capacity and volume, while others focus on certification, regulatory compliance, or product specialization. The report analyzes how these competitive dynamics influence pricing, availability, and innovation. It also discusses how recent developments, or the lack thereof in certain periods, reflect the stability and maturity of the industry. Stakeholders can use this competitive intelligence to benchmark their own operations, identify potential partners or competitors, and anticipate market shifts driven by the actions of key players.
Strategic Imperatives for 2026 and the Forecast Horizon
As we look ahead to the rest of 2026 and the subsequent years leading to 2032, several strategic imperatives emerge for businesses involved in the Methyl Orthoformate value chain. First, supply chain resilience must be a priority. Given the reliance on specific raw materials and production methods, disruptions in feedstock availability or logistics can have cascading effects. Diversifying suppliers, securing long-term contracts for hydrogen cyanide or methanol, and investing in inventory management can mitigate these risks.
Second, quality and compliance are increasingly decisive factors. As downstream industries, particularly pharmaceuticals, demand higher purity and traceability, manufacturers and distributors must ensure their processes meet evolving standards. Regulatory listings, such as those related to green additives or safety certifications, can open doors to new markets and enhance brand reputation. Companies that proactively engage with regulatory frameworks and invest in quality assurance systems will be better positioned to capture premium segments.
Third, regional diversification and market intelligence are crucial. While Asia Pacific remains a powerhouse, opportunities exist in other regions depending on application mix and trade flows. Understanding local demand drivers, regulatory requirements, and competitive dynamics in each region allows organizations to tailor their strategies effectively. The forecast period suggests continued growth, but this growth may be uneven across regions and applications. Real-time intelligence and detailed analysis are required to navigate these variations successfully.
Finally, innovation and capacity planning should be aligned with long-term market projections. The projected growth rate implies that demand will expand steadily, offering opportunities for producers to scale operations or for distributors to broaden their offerings. However, capacity expansion must be calibrated to avoid oversupply in specific segments. Detailed forecasts by application and type, as provided in our full report, enable precise capacity planning and investment decisions that maximize returns and minimize risk.
Unlocking Complete Market Intelligence
This overview provides a strategic snapshot of the Methyl Orthoformate market, highlighting the growth trajectory, key drivers, competitive dynamics, and critical considerations for 2026. However, the complexities of this market require a deeper level of analysis than a summary can provide. To fully support your strategic decision-making, we invite you to access the complete PW Consulting Market Research on Methyl Orthoformate.
The full report offers granular data and actionable insights, including detailed segmentation analysis, comprehensive competitor benchmarking, precise volume and revenue breakdowns by region and application type, and an exhaustive review of production technologies and regulatory impacts. It contains the specific data points, tables, and strategic frameworks necessary to build robust business cases, negotiate effectively, and capitalize on market opportunities.
Do not rely on surface-level trends. Equip your organization with the depth of intelligence required to lead in this evolving market. Access the full research today to gain the complete picture of the Methyl Orthoformate market and secure the strategic advantage you need for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Methyl Orthoformate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Home Blood Pressure Monitor Market to Hit $2.41B by 2032, 9.2% CAGR
By PW Consulting, 2026-09-07
The Pulse of the Home: Strategic Intelligence in the Automated Home Blood Pressure Monitors Market
The global health technology landscape is undergoing a fundamental shift. As healthcare systems worldwide grapple with the burden of chronic cardiovascular conditions, the locus of care is moving decisively from the clinic to the living room. At the center of this transformation lies the Automated Home Blood Pressure Monitors Market. For executives, investors, and strategic planners, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for informed decision-making in 2026 and beyond.
Worldwide Multi-Sensor Analyzer Market
Our latest comprehensive market research offering provides a granular examination of this sector. This document serves as a strategic primer, outlining the macro-economic forces, competitive dynamics, and regulatory realities that define the industry. While we share high-level insights here to establish context, the full depth of our proprietary data and segmentation analysis is reserved for the complete report, ensuring that our clients possess the competitive edge of exclusive intelligence.
Water Pump Bearing Seal Ring Market
Market Trajectory and Historical Context
The evolution of the automated home blood pressure monitor market over the past half-decade tells a story of resilience and acceleration. Historical data indicates a clear upward trend in market valuation, reflecting increased consumer awareness and the integration of digital health tools into daily routines. After navigating the volatility of the early 2020s, the market has stabilized and entered a phase of robust growth.
Portable Unmanned Surface Vessel Market
Looking back from a base year of 2025, the market demonstrated consistent expansion throughout the historical period. This growth was not linear but was influenced by broader economic conditions, supply chain dynamics, and shifting healthcare priorities. As we pivot to the forecast period extending through 2032, the outlook remains highly positive. The market is projected to expand significantly, driven by an aging global population, the rising prevalence of hypertension, and the increasing adoption of connected health devices.
The compound annual growth rate (CAGR) anticipated over the forecast horizon signals a healthy expansion trajectory. This growth rate suggests that demand will outpace many general consumer electronics categories, underscored by the critical nature of cardiovascular health management. For businesses operating in this space, the implication is clear: the market is large enough to accommodate new entrants while substantial enough to reward established players who can innovate effectively. However, capturing this growth requires more than just manufacturing capability; it demands a nuanced understanding of where value is being created and how revenue streams are shifting across different modalities.
While the top-line figures indicate a thriving ecosystem, the composition of that revenue is complex. The shift from basic analog devices to sophisticated, connectivity-enabled automated units is reshaping the revenue mix. Our analysis delves into these shifts, identifying which product architectures are gaining traction and how pricing strategies are evolving in response to market maturity. The full breakdown of these revenue streams, including the relative weight of different form factors and their contribution to total market value, is detailed in the complete report.
The Competitive Arena
The competitive landscape of the automated home blood pressure monitor market is characterized by a mix of established medical device giants and agile regional manufacturers. Market concentration remains significant, with a handful of key players commanding a substantial portion of the market share. This oligopolistic tendency suggests high barriers to entry regarding brand trust, regulatory compliance, and distribution networks, although recent activities indicate that these barriers are being challenged by innovative competitors.
Leading the charge are organizations such as Omron Healthcare and A&D Medical. Headquartered in Kyoto, Japan, these companies have long set the standard for clinical validation and accuracy. Omron, for instance, has integrated AI-enhanced features and connectivity into their upper-arm and wrist models, positioning themselves at the intersection of hardware and digital health platforms. Their focus on features like AFib detection illustrates a strategy of moving beyond simple measurement to comprehensive health monitoring. Similarly, A&D Medical continues to emphasize premium accuracy technology and multi-user capabilities, catering to households where multiple members require monitoring.
Simultaneously, the landscape is being reshaped by manufacturers based in China, particularly in the Guangdong and Zhejiang provinces. Companies like Hetaida Technology, Shenzhen Urion Technology, Shenzhen AOJ Medical Technology, and JOYTECH Healthcare have been aggressive in expanding their footprint. Their strategy often revolves around securing regulatory clearances to access broader markets, particularly in the United States. For example, throughout 2025 and into 2026, several of these entities received FDA 510(k) clearance for various series of automated electronic monitors. Hetaida secured clearance for their D6606US and D6607US series, while Shenzhen Urion cleared their U90B series, which includes multiple variants ranging from standard to ultra models. Shenzhen AOJ Medical and JOYTECH also finalized clearances for their respective arm-type digital monitors.
This wave of regulatory approvals is not merely a bureaucratic milestone; it is a strategic market entry ticket. It allows these manufacturers to compete in regulated markets where clinical validation is paramount. In the United States, Welch Allyn, now part of Hill-Rom Holdings Inc., remains a notable supplier, offering user-friendly interfaces like the Home 1700 Series designed for ease of use with one-button operation. The competition here is fierce, blending brand heritage with price competitiveness and technological differentiation. Our full report provides a detailed comparative analysis of these key companies, examining their product pipelines, strategic positioning, and the specific impact of their recent developments on market share dynamics.
Navigating Dynamics and Barriers
Success in the automated home blood pressure monitors market requires navigating a complex web of regulatory and economic dynamics. The regulatory environment is stringent. In the United States, FDA 510(k) clearance is mandatory for all automated home blood pressure monitors intended for consumer use. Manufacturers must demonstrate substantial equivalence to predicate devices via clinical validation protocols. This requirement acts as a filter, ensuring that only devices meeting specific accuracy and safety standards reach the consumer. For strategic planners, this means that time-to-market is heavily influenced by regulatory timelines, and compliance capability is a core competency rather than a back-office function.
Beyond regulation, reimbursement policies play a critical role in shaping demand, particularly in the United States. There is a distinct divergence in coverage policies between standard automated home monitors and ambulatory blood pressure monitors (ABPM). Medicare, for instance, does not cover standard automated home blood pressure monitors. However, it does cover ambulatory blood pressure monitors once per year when ordered by a doctor for patients with white coat syndrome or masked hypertension. This distinction creates a nuanced market dynamic where consumer out-of-pocket expenditure drives the home monitor segment, while clinical prescription drives the ambulatory segment. Understanding this split is vital for pricing strategies and market segmentation.
Supply chain and material costs also present variable dynamics. In the context of cost management, single-use disposable cuffs are projected to account for the majority of the consumable segment. This trend is driven by providers and some home care scenarios prioritizing infection control and hygiene. For manufacturers, this highlights the importance of the consumables ecosystem attached to the hardware. It also suggests that business models may need to account for recurring revenue from disposables, not just one-time hardware sales.
Strategic Implications for 2026 Decision-Making
As we move further into the forecast period, the strategic implications for stakeholders are profound. The data suggests that the market is not just growing in size but evolving in complexity. Companies that view blood pressure monitors as simple commodities risk obsolescence. The future belongs to those who can integrate accuracy, connectivity, and user experience into a cohesive value proposition.
For product development teams, the focus must be on validating clinical accuracy while enhancing digital integration. The success of companies like Omron demonstrates that features beyond blood pressure measurement, such as arrhythmia detection, can differentiate products in a crowded market. For market entry strategists, the recent wave of FDA clearances among Asian manufacturers indicates that the supply base is diversifying. This offers opportunities for partnership, licensing, or competitive benchmarking, but it also raises the bar for quality assurance.
Financial planners and investors must look beyond the top-line market size. The concentration of market share among top players suggests that partnerships or acquisitions might be necessary to gain immediate scale. However, the growth rate implies there is still room for niche players who can target specific demographics or geographic regions with tailored solutions. The revenue units involved operate in the millions, indicating a substantial addressable market, but the allocation of that revenue across regions and applications requires careful strategic alignment.
Operational leaders must also consider the regulatory and reimbursement landscape as part of their risk management framework. The distinction between covered ambulatory devices and non-covered home monitors influences marketing channels. Direct-to-consumer marketing becomes essential for home monitors, whereas B2B channels with healthcare providers are crucial for ambulatory devices. Misunderstanding this dynamic can lead to inefficient resource allocation.
The Value of Deep-Dive Intelligence
While the overview provided here highlights the broad strokes of market growth, competitive pressure, and regulatory hurdles, it inevitably omits the granular data required for execution. Strategic decisions require specifics: exact valuation figures for specific years, detailed segmentation splits by region and type, and precise market concentration metrics.
Our complete market research report fills these gaps. It dissects the market size evolution from the historical base through the full forecast period, providing the numerical backbone for financial modeling. It breaks down the segmentation splits, revealing the relative performance of different monitoring types and regional markets without exposing the proprietary methodology used to derive these figures. This allows clients to benchmark their own performance against the market average and identify high-growth pockets that are not visible from the macro level.
Furthermore, the full report expands on the competitive landscape with detailed profiles of key companies, including their headquarters, strategic focus, and recent regulatory milestones. It contextualizes these profiles within the broader industry noise, such as reimbursement shifts and material cost projections, providing a holistic view of the operating environment. This level of detail transforms general awareness into actionable intelligence.
Conclusion: Monitoring the Future
The Automated Home Blood Pressure Monitors Market stands at a critical juncture. The convergence of an aging demographic, technological advancement, and regulatory standardization is creating a fertile ground for growth. However, the path to capturing this value is fraught with competition and compliance challenges. The firms that succeed in 2026 and beyond will be those that can interpret these signals accurately and act with precision.
This market research publication is designed to be that navigational instrument. By providing a clear view of the past trends and future projections, we empower leaders to make decisions grounded in data rather than assumption. The macro trends indicate a strong tailwind, but the micro dynamics determine who will ride the wave successfully.
To access the full spectrum of data, including the specific market size figures, detailed segmentation analysis, and comprehensive company profiles discussed implicitly above, we invite you to explore the complete report. The depth of intelligence contained within is crafted to support high-stakes decisions, ensuring that your strategy is as robust as the market itself.
For detailed analysis of this topic, please visit the official page: Automated Home Blood Pressure Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Composite Insulated Panels Market Hits $250M in 2025, Projects 5.8% CAGR Through 2032
By PW Consulting, 2026-09-07
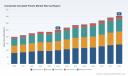
Navigating the Next Wave: Strategic Intelligence for the Composite Insulated Panels Market (2026-2032)
Executive Summary: The Imperative for Precision in 2026
The global construction and industrial refrigeration sectors are entering a period of recalibration. As supply chains adjust to new trade realities and building codes tighten around energy efficiency and fire safety, the materials used to envelope these structures are under scrutiny. Composite Insulated Panels (CIPs) remain a cornerstone of modern building envelopes and cold chain infrastructure, but the strategic landscape defined them in 2020 has shifted materially by 2026.
Pre-Thickening Screw Sludge Dewatering Machine Market
PW Consulting latest market research offers a comprehensive view of this transition. Our analysis covers the historical trajectory from 2020 through 2025 and projects market behavior through the forecast period ending in 2032. For executives, procurement leaders, and investors, understanding the nuanced shifts in volume, value, and competitive positioning is no longer optional—it is a prerequisite for capital allocation and product roadmap planning.
Folding Turnover Box Market
The market has demonstrated resilience despite macroeconomic headwinds. Starting from a base of 200.0 million USD in 2020, the sector grew to 250.0 million USD by 2025. While 2024 saw a slight contraction to 236.51 million USD due to raw material volatility, the recovery in 2025 signals a return to structural growth. Looking forward, the market is expected to reach 267.62 million USD in 2026 and continue expanding toward 355.0 million USD by 2032. This trajectory implies a Compound Annual Growth Rate (CAGR) of 5.8 percent over the forecast horizon.
Wheeled Rescue Robot Market
However, aggregate numbers only tell part of the story. The real value of this research lies in dissecting the drivers behind these figures, identifying where concentration risks exist, and understanding how key players are positioning themselves against regulatory and geopolitical shifts.
Market Structure and Concentration Dynamics
Understanding the competitive intensity is vital for assessing market entry barriers and partnership opportunities. The Composite Insulated Panels market is moderately concentrated, suggesting that while large players dominate significant shares, there remains room for specialized regional competitors to thrive. Our data indicates a CR3 of 45.5 percent and a CR5 of 58.2 percent.
This concentration level suggests that the top five players control more than half of the market revenue, creating a environment where pricing power and supply chain leverage are often held by established incumbents. However, the remaining market share is distributed among a long tail of manufacturers, particularly in emerging regions or niche application segments. For new entrants or existing players looking to expand, the strategy often involves targeting segments where the giants are less active or where specific regional regulations create localized demand pockets.
The research delves into the operational footprints of these key entities, analyzing how their headquarters locations and manufacturing capacities align with regional demand hotspots. This geographic alignment is becoming increasingly critical as trade barriers reshape logistics costs.
Competitive Landscape: Key Players and Recent Moves
The competitive arena is defined by a mix of global giants and specialized regional manufacturers. Our report profiles several core companies that are shaping the industry standards and capacity trends.
- Kingspan Group (Ireland): As a global leader in high-performance insulated panel systems, Kingspan continues to expand its footprint. Their recent activities highlight a focus on mineral fibre technology and capacity expansion in key European markets. Investors and partners should note the strategic implication of their expanded capacity in Poland and France, which signals a commitment to serving the European industrial and commercial sectors despite broader economic uncertainty.
- Metl-Span and Nucor Insulated Panel Group (United States): Operating out of Lewisville, Texas, these entities represent a significant force in the North American market. Nucor Insulated Panel Group operates both Metl-Span and CENTRIA brands, producing architectural insulated metal composite panels. Their dual-brand strategy allows them to address both industrial functional needs and high-end architectural requirements, a differentiation strategy worth examining for competitors in other regions.
- Hemsec (United Kingdom): Focusing on high-performance steel and timber structural insulated panels (SIPs), Hemsec serves commercial and controlled environments. Their positioning is particularly relevant in the context of UK and European building safety regulations.
- Assan Panel (Turkey) and Isopan (Italy): These manufacturers highlight the strength of European and Mediterranean production hubs. Assan Panel produces sandwich composite insulated panels for roofs, walls, and cold storage, while Isopan, part of the Manni Group, manufactures metal sandwich insulated panels with rock wool or PIR cores. Their proximity to both European and Middle Eastern markets allows for flexible supply chain responses.
- ArcelorMittal Construction (Luxembourg): A major player in PIR and mineral wool insulated sandwich panels, including the Promisol line. Their recent secured multi-year supply agreement with a major European logistics firm for cold storage sandwich panels underscores the growing demand in the logistics and cold chain sector. This move indicates a strategic pivot toward long-term supply contracts in high-growth application areas.
Recent developments in early 2026 further illustrate the dynamic nature of this landscape. Kingspan Group launched a new Mineral Fibre Insulated Panel Line with expanded capacity in Poland and France, reinforcing the push toward fire-resistant and high-performance materials. Simultaneously, ArcelorMittal Construction secured a multi-year supply agreement with a major European logistics firm, highlighting the stability sought by large-scale cold storage operators.
Segmentation Insights: Type, Application, and Regional Nuances
The market is not monolithic. Our research segments the industry by type, application, and region to reveal where specific growth vectors are emerging. While aggregate data shows overall growth, the composition of that growth varies significantly across categories.
In terms of product type, the market encompasses Expanded Polystyrene, Rigid Polyurethane, Polyisocyanurate, and Glass Wool cores. Each material offers different trade-offs regarding thermal performance, fire resistance, and cost. The choice of core material is increasingly influenced by local building codes and insurance requirements, particularly in commercial high-rises and cold storage facilities.
Regarding applications, the demand is driven primarily by Building Walls and Building Roofs, which constitute the bulk of construction-related insulation needs. However, the Cold Storage segment represents a critical high-growth niche. As global supply chains emphasize temperature-controlled logistics to reduce food waste and meet pharmaceutical storage standards, the demand for specialized insulated panels in this sector is outpacing general construction in certain regions.
Regionally, the market distribution reflects established industrial bases as well as emerging construction hubs. North America remains a significant contributor, driven by commercial industrial construction and retrofitting. Europe follows closely, influenced heavily by energy efficiency directives and fire safety regulations. The Asia Pacific region, while historically diverse in its construction materials, is seeing increased adoption of composite panels due to urbanization and cold chain infrastructure development. Latin America and the Mideast and Africa regions represent emerging opportunities where infrastructure investment is translating into material demand.
Our full report provides a detailed breakdown of these segments, allowing clients to identify which specific product-application combinations offer the highest margin potential in their target geography. We avoid generic generalizations, instead providing the granular data needed to model regional revenue potential accurately.
Industry Dynamics: Regulations, Costs, and Geopolitics
The external environment is perhaps the most volatile variable in the forecast model. Several converging factors are reshaping the cost structure and demand drivers for Composite Insulated Panels in 2026 and beyond.
Raw Material Volatility and Tariffs: Manufacturers are currently facing elevated costs for steel, polyurethane, and mineral wool. Accelerated tariffs on imported building materials in the United States and select European markets have squeezed margins. Our analysis incorporates these cost pressures into the pricing forecasts, helping clients understand where price increases may be absorbed by the market and where they might stall demand.
Geopolitical Tensions: Cross-border trade restrictions are driving raw material shortages and price volatility for steel and specialty insulation imports. This instability affects not just the cost of goods sold but also the reliability of supply chains. Companies are forced to reconsider their sourcing strategies, potentially favoring local or near-shore manufacturing partners to mitigate risk.
Regulatory Pressures on Safety and Efficiency: Building codes are becoming stricter. In the European Union, building safety regulations are accelerating demand for fire-resistant sandwich panels. This regulatory shift is prompting new product lines from major manufacturers like ArcelorMittal Construction, moving the market toward higher-specification materials that command premium pricing.
Construction Material Cost Parity: An interesting dynamic is emerging in the residential and light commercial sectors. According to recent data from the Structural Insulated Panel Association, framing lumber prices reached 483 USD per 1,000 board feet in April 2025, a 23.5 percent increase. This spike has narrowed the cost gap for structural insulated panels versus traditional framing. For the first time in recent cycles, SIPs are becoming cost-competitive not just on performance metrics but on raw material cost parity, potentially unlocking new demand segments in residential construction.
These dynamics create a complex operating environment. A strategy that worked in 2022 may be obsolete in 2026 due to changes in tariff structures or fire safety compliance costs. Our report contextualizes these factors, offering scenario analysis that helps leadership teams prepare for various regulatory and economic outcomes.
Strategic Value for 2026 Decision Making
Why does this level of detail matter for your 2026 planning? Because the margin for error is shrinking.
1. Capital Investment Timing: With the market projected to grow from 267.62 million USD in 2026 to 355.0 million USD by 2032, the question is not whether the market is growing, but where to deploy capital for maximum return. Are you investing in capacity for PIR cores in Europe to meet fire regulations, or expanding cold storage panel production to meet logistics demand? The report helps prioritize these investments.
2. Supply Chain Resilience: Given the tariff and geopolitical noise, understanding the supply chain vulnerabilities of your competitors and partners is crucial. Knowing which regions are most exposed to steel import tariffs allows you to adjust procurement contracts or seek alternative sourcing before costs escalate further.
3. Product Portfolio Alignment: The divergence in demand between Building Walls, Roofs, and Cold Storage means a one-size-fits-all product strategy is risky. The research highlights which applications are driving volume versus value. For instance, while Building Walls may offer higher volume, Cold Storage might offer higher margins or longer contract stability.
4. Competitive Benchmarking: With a CR5 of 58.2 percent, the top players have significant influence over market standards and pricing. Understanding their recent moves—such as Kingspan capacity expansions or ArcelorMittal supply agreements—allows smaller players to find whitespace opportunities or larger players to anticipate competitive retaliation.
5. Regulatory Compliance as a Moat: Fire safety and energy efficiency regulations are creating barriers to entry for non-compliant products. Our analysis identifies which segments are most affected by these regulations and how compliance costs are likely to evolve, turning regulatory adherence into a competitive advantage rather than just a cost center.
Conclusion: Accessing the Full Intelligence Picture
The Composite Insulated Panels market is at an inflection point. The convergence of energy efficiency mandates, cold chain expansion, and volatile raw material costs creates a landscape that rewards data-driven decision-making. The historical growth from 200.0 million USD in 2020 to a projected 355.0 million USD in 2032 represents a significant opportunity, but capturing that value requires more than just tracking top-line revenue.
It requires understanding the segmentation splits, the concentration of power among key manufacturers, and the specific regulatory and geopolitical headwinds shaping the next six years. PW Consulting research is designed to provide this clarity. We move beyond surface-level summaries to deliver the actionable intelligence needed to navigate complex market dynamics.
For organizations serious about positioning themselves in this sector, the aggregate numbers are just the starting point. The real strategic advantage lies in the detail: the specific regional growth rates, the application-based margin structures, and the competitive maneuvers of the industry leaders profiled in this report.
To access the complete dataset, including detailed segmentation splits, regional revenue breakdowns, and full competitor profiles, we invite you to explore the full market research publication. The insights contained within are structured to support immediate strategic planning cycles for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Composite Insulated Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Vehicle Market Hits $1.4B in 2025, Projects $13.9B by 2032 at 38.5% CAGR
By PW Consulting, 2026-09-07
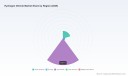
The Hydrogen Vehicle Market at an Inflection Point: Strategic Intelligence for 2026 and Beyond
The global automotive industry is navigating a period of profound structural transformation, and within that shift, hydrogen-powered mobility has emerged as one of the most consequential—and most contested—vectors of future growth. For executives, investors, and policy architects, the question is no longer whether hydrogen vehicles will carve out a meaningful commercial footprint, but where exactly the value will accumulate, which technological pathways will dominate, and how regulatory momentum will reshape competitive positioning over the next seven years. Our latest Hydrogen Vehicle Market research report delivers a rigorous, forward-looking intelligence framework designed specifically to answer those questions and to equip leadership teams with the clarity required for decisive 2026 planning.
Block Device Replication and Recovery Management Software Market
The market’s trajectory over the past half-decade has been striking. From a baseline of approximately 0.3 billion USD in 2020, revenue expanded to 0.39 billion in 2021, 0.51 billion in 2022, and 0.63 billion in 2023, before accelerating sharply to 1.03 billion in 2024 and reaching 1.4 billion in our 2025 base year. That progression alone signals a transition from experimental pilot phases to early commercial scaling. Looking ahead, the forecast window through 2032 maps an even more dramatic expansion curve, with projections reaching 1.94 billion in 2026, 2.73 billion in 2027, 3.7 billion in 2028, continuing to 5.15 billion in 2029, 7.09 billion in 2030, 10.0 billion in 2031, and ultimately 13.9 billion in 2032. These figures translate into a compound annual growth rate of 38.5 percent across the entire forecast horizon, a pace that places hydrogen vehicles among the fastest-scaling mobility segments in the broader decarbonization landscape. Yet raw growth rates, while essential, are only the starting point for actionable strategy. The real value lies in understanding the structural forces driving that expansion, the competitive fault lines emerging beneath the surface, and the regulatory and infrastructure variables that will determine which organizations capture disproportionate share.
Worldwide Touch Screen Vending Machine Market
Decoding the Macro Trajectory: Why 2026 Is a Pivotal Decision Year
Any market moving from a 1.4-billion-dollar base toward a 13.9-billion-dollar endpoint over a seven-year horizon demands more than top-line optimism; it requires a disciplined dissection of demand drivers, supply-chain readiness, and regional deployment patterns. The data sequence from 2020 through 2025 reveals an inflection that began in earnest during 2024, when reported revenue more than doubled year-over-year. That acceleration was not a statistical anomaly but a reflection of converging catalysts: maturing fuel cell durability, declining balance-of-plant costs, expanding refueling networks in select corridors, and an increasingly urgent corporate mandate to decarbonize heavy-duty and long-haul operations where battery-electric architectures face inherent range and payload constraints.
Worldwide Remote Sales Agents Market
For 2026 specifically, the forecasted jump to 1.94 billion USD carries strategic implications that ripple across procurement, R&D allocation, and partnership structuring. Organizations that treat 2026 as a mere continuation of prior-year trends risk underinvesting in the engineering talent, supplier contracts, and regulatory compliance frameworks needed to participate meaningfully in the next phase. Conversely, those that recognize the 38.5 percent CAGR as a signal of compounding ecosystem maturation—rather than a fleeting growth spike—can position themselves to secure early-mover advantages in component sourcing, fleet integration, and customer incentive utilization. The forecast numbers alone tell a compelling story, but the operational translation of those numbers depends on granular insight into application-specific adoption curves, regional incentive architectures, and the shifting economics of hydrogen production and distribution. Those deeper layers of analysis are precisely where this report delivers its most differentiated value, and they are structured to remain behind the access boundary of the full publication so that subscribers receive uncompromised, decision-grade intelligence.
Inside the Report: Operational Intelligence Designed for Execution
This research is engineered not as an abstract market overview but as a working toolkit for strategy, finance, and operational teams. The report opens with a comprehensive market sizing and forecasting architecture that traces historical performance from 2020 through 2025 and projects forward across the 2026–2032 window, with meticulous attention to the assumptions underpinning each forecast revision. Revenue trajectories are mapped against demand-side indicators, technology-cost curves, and policy calendars, giving readers a transparent view of how growth scenarios are constructed and where sensitivity analysis matters most.
From there, the analysis dissects the market across multiple dimensional lenses. A regional perspective examines deployment leaders, infrastructure readiness gradients, and the policy environments that are either accelerating or constraining hydrogen vehicle adoption in different geographies. A type-based breakdown contrasts fuel cell vehicle architectures with alternative powertrain configurations, highlighting where investment and engineering effort are concentrating and which pathways are gaining commercial traction. An application-focused evaluation separates passenger car deployments from commercial vehicle integrations, scrutinizing the distinct Total Cost of Ownership dynamics, operational constraints, and fleet procurement cycles that shape each segment.
Beyond segmentation, the report delivers a competitive landscape assessment built on company profiles, strategic positioning analysis, and recent corporate activity tracking. Readers will find structured evaluations of the organizations that are defining the market’s shape, alongside a timeline of product introductions, facility investments, and program adjustments that reveal where incumbents and challengers are placing their bets. A dedicated regulatory and policy module maps the incentive programs, emissions mandates, and subsidy architectures that directly influence purchase economics and deployment timelines, with particular attention to how shifting administrative decisions can rapidly alter regional viability. The publication also integrates infrastructure ecosystem considerations, supply-chain risk mapping, and scenario-planning templates that allow leadership teams to stress-test their hydrogen strategies against alternative future states. Every section is written with an executive audience in mind, prioritizing clarity, comparability, and immediate applicability over academic exposition.
The Competitive Arena: Where Leaders Are Positioning for Scale
The hydrogen vehicle market is not a diffuse, undifferentiated space. It is increasingly defined by a concentrated set of players that are competing across passenger vehicles, heavy-duty trucks, and fuel cell system supply, often simultaneously. The competitive structure reflects a blend of legacy automotive engineering depth, specialized fuel cell expertise, and aggressive commercial-vehicle commercialization efforts. Understanding who is advancing which platform, and why, is essential for any organization evaluating partnership opportunities, procurement dependencies, or competitive threats.
Toyota Motor Corporation continues to anchor its hydrogen strategy around the Mirai fuel cell sedan and the Crown FCEV, while simultaneously extending its reach into heavy-duty applications through integrated powertrain kits for trucks. In March 2025, Toyota introduced the 2025 Mirai equipped with a third-generation fuel cell system that delivers a 20 percent improvement in range, a milestone that underscores the company’s emphasis on iterative system refinement and consumer-facing range credibility. Hyundai Motor Company, based in Seoul, has pursued a dual passenger-and-commercial approach, producing the NEXO fuel cell SUV with 190 kW output and developing integrated systems for trucks such as the Xcient. In November 2025, Hyundai unveiled the all-new NEXO, reaffirming 190 kW output while extending the range to 826 km, a product launch that signals both performance maturation and a commitment to maintaining visibility in the passenger fuel cell segment.
Honda Motor Co., Ltd., headquartered in Tokyo, has maintained its presence through the CR-V e:FCEV plug-in fuel cell vehicle and next-generation fuel cell system development, positioning itself at the intersection of plug-in flexibility and hydrogen range extension. In the heavy-duty and commercial sphere, Hyzon Motors Inc., operating from Bolingbrook, Illinois, has focused on hydrogen fuel cell systems for heavy-duty refuse trucks, an application where depot-based refueling and predictable routes can create early operational wins. Nikola Corporation, based in Phoenix, Arizona, produces the Tre hydrogen-electric semi-truck with a fuel cell powertrain, targeting the long-haul segment where hydrogen’s energy density advantages are most strategically relevant. Daimler Truck AG, from Stuttgart, is advancing the GenH2 hydrogen fuel cell trucks for commercial applications, while Volvo Group, headquartered in Gothenburg, produces the FH Electric FCEV for heavy-duty transport, both reflecting European truck manufacturers’ conviction that fuel cell architectures will play a meaningful role in commercial decarbonization.
The competitive field also includes system-level specialists and diverging corporate strategies. BMW Group, from Munich, is developing and supplying hydrogen fuel cell systems for future passenger vehicles, with series production planned for 2028. In September 2025, BMW began construction of Plant Steyr for third-generation fuel cell systems, a facility investment that signals long-horizon commitment and manufacturing readiness. Symbio SAS, based in Grenoble, France, supplies fuel cell systems for heavy-duty hydrogen vehicles and trucks, representing the growing importance of tier-one system integrators that enable vehicle manufacturers to access fuel cell technology without building every component in-house.
Yet the competitive landscape is not defined solely by advancement; it is also shaped by withdrawal and recalibration. In October 2025, General Motors Company ended its next-generation hydrogen fuel cell development program and halted production at the Fuel Cell System Manufacturing LLC joint venture, a decision that illustrates how corporate resource allocation, technology prioritization, and strategic fit can redirect even well-resourced organizations away from hydrogen pathways. Meanwhile, Stellantis announced the full termination of its light-commercial vehicle hydrogen fuel cell development program in Europe, citing infrastructure limitations—a move that highlights how refueling network adequacy and regional deployment economics can become decisive constraints on program viability. These divergent corporate decisions, taken together, reveal a market in which not every manufacturer will pursue every segment, and where strategic selectivity is becoming as important as technological capability.
Regulatory Tailwinds, Subsidy Friction, and the New Normal of Policy Risk
Hydrogen vehicle adoption does not unfold in a regulatory vacuum. Across major markets, policy frameworks are simultaneously enabling and complicating deployment, creating a dynamic environment in which incentive design, emissions mandates, and procurement programs directly influence purchase economics and fleet planning timelines. California remains a critical bellwether. The California Air Resources Board 2025 Annual Evaluation projects FCEV sales growth through 2031 and introduces specific discount programs for Toyota Mirai buyers, a targeted incentive structure that demonstrates how regional regulators are attempting to reduce upfront purchase barriers while maintaining momentum toward broader zero-emission goals. Such programs can materially shift consumer and fleet willingness to adopt, particularly in the passenger segment where range confidence and refueling access remain purchase decision factors.
At the same time, policy uncertainty can quickly introduce friction. Hyzon Motors cited the suspension of customer purchases due to uncertainty in California’s Hybrid and Zero-Emission Truck and Bus Voucher Incentive Project subsidies, a development that underscores how dependent some commercial deployments remain on the continuity and predictability of public funding mechanisms. When subsidy calendars shift or administrative decisions introduce pause periods, order pipelines, production scheduling, and supplier commitments can all be disrupted. This vulnerability is not unique to a single company; it reflects a broader structural reality that hydrogen vehicle commercialization, especially in its early scaling phase, continues to rely on a layered combination of environmental regulation, direct incentives, infrastructure funding, and fleet procurement mandates.
The regulatory landscape therefore demands continuous monitoring rather than static compliance planning. Fleet operators and vehicle manufacturers alike must interpret not only what incentives exist today, but how they are likely to evolve, where eligibility criteria may tighten, and which administrative decisions could alter regional competitiveness. The report’s policy analysis module is built to support that kind of forward-looking interpretation, mapping regulatory trajectories and incentive architectures in a way that helps organizations anticipate rather than merely react to policy shifts.
Concentration, Risk, and the Strategic Case for Deep Intelligence
Market structure matters as much as market size. The hydrogen vehicle sector exhibits a notable degree of concentration among its leading participants, with the top three firms accounting for approximately 65 percent of market share and the top five reaching roughly 70 percent. That concentration carries strategic implications. For new entrants and partnership-seeking organizations, it means that a relatively small number of players control a disproportionate share of technology development, manufacturing capability, and customer relationships. For existing participants, it means that competitive positioning is increasingly dependent on differentiated system performance, scalable production capacity, and the ability to secure reliable hydrogen supply and refueling access. Concentration also amplifies the importance of tracking competitor moves closely, because strategic announcements, product launches, and program terminations from a handful of firms can reshape the entire market’s trajectory in a single quarter.
Risk management in this environment requires more than awareness of headline growth rates. It requires visibility into the assumptions behind those rates, the regional and application-level distribution of demand, the durability of incentive programs, and the operational readiness of the hydrogen supply chain. It requires clarity on which vehicle segments are genuinely reaching commercial viability and which remain constrained by infrastructure gaps or economics. It requires the ability to distinguish between sustained momentum and temporary policy-driven spikes. The full report is designed to provide that depth, preserving the segment-specific breakdowns, regional nuances, and quantitative sensitivity analyses that executives need when they are allocating capital, negotiating supplier agreements, or deciding whether to commit to hydrogen-powered fleet roadmaps in 2026.
Conclusion: From Market Awareness to Competitive Advantage
The hydrogen vehicle market is entering a phase in which growth is no longer theoretical, but neither is it automatically guaranteed for every participant. The jump from a 1.4-billion-dollar base year in 2025 toward a 13.9-billion-dollar projection by 2032 reflects real technological progress, genuine commercial interest, and a policy environment that continues to favor zero-emission mobility. Yet the same environment also contains subsidy uncertainty, regional infrastructure limitations, and corporate strategy divergence that can separate winners from followers with surprising speed. In that context, the organizations that will navigate 2026 most effectively are those that move beyond surface-level market awareness and invest in decision-grade intelligence.
This Hydrogen Vehicle Market report has been built to serve that need. It combines rigorous historical analysis, a disciplined 2026–2032 forecast framework, a detailed competitive and regulatory assessment, and practical segmentation lenses that translate macro growth into operational insight. The publication deliberately reserves its most granular regional, application-specific, and segment-level data for the full report, ensuring that subscribers receive a complete, uncompromised intelligence asset rather than a summary synthesized for public consumption. For leadership teams preparing strategy, budgeting, partnership evaluations, and product roadmap decisions for 2026, that depth is not an optional enhancement—it is the difference between a directional hypothesis and an executable plan.
The next phase of hydrogen mobility will be shaped by the precision of the decisions made today. Access the complete report to obtain the full market architecture, segment-level breakdowns, and forward-looking competitive intelligence required to position your organization with confidence in a market expanding at 38.5 percent CAGR and evolving faster than most strategic planning cycles are designed to accommodate.
For detailed analysis of this topic, please visit the official page: Hydrogen Vehicle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glossmeter Market Hits $55M in 2025, Projected $75.57M by 2032 at 4.7% CAGR
By PW Consulting, 2026-09-07
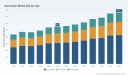
Avoiding the Fade: Strategic Intelligence in the 2026 Glossmeter Market
Setting the Stage for Quality Control and Surface Analytics
As global manufacturing standards tighten and consumer expectations for surface finish precision escalate, the glossmeter market has evolved from a niche testing utility into a critical component of industrial quality assurance. PW Consulting's latest market research release offers a comprehensive examination of this sector, providing enterprise decision-makers with the foresight needed to navigate the period from 2026 through 2032. This document serves as an executive introduction to the full study, outlining the trajectory of the industry while reserving granular segmentation data for the complete proprietary report.
Commercial Convection Speed Oven Market
The global glossmeter market has demonstrated resilience and steady expansion over the past half-decade, recovering from minor fluctuations seen in the early 2020s to establish a robust growth trajectory. Current market size estimates place the industry firmly above the mid-fifty million USD threshold, reflecting a compound annual growth rate of approximately 4.7 percent. This consistent upward movement signals more than simple recovery; it indicates a structural shift in how industries prioritize surface metrology, integrating gloss measurement into broader quality management systems that demand repeatability, traceability, and regulatory adherence. For stakeholders evaluating capital allocation in testing equipment, instrument procurement, or R&D investment, understanding these macro trends is the first step toward informed strategy formulation.
Worldwide Lithium Lanthanum Zirconium Oxide(LLZO) Market
The forecast horizon extends through 2032, a period during which the market is expected to breach the seventy-five million USD mark. Such growth is not merely arithmetic. It reflects the compounding effect of technological maturation, regulatory reinforcement, and the diffusion of precision measurement capabilities into emerging application verticals. The research captures the inflection points that will define competitive advantage, highlighting where capacity expansion, product innovation, and service infrastructure will yield the highest strategic returns. By mapping these dynamics, the report equips procurement leaders, quality directors, and investment analysts with the context needed to challenge assumptions and align operational roadmaps with market realities.
Worldwide Mortar Sprayer Market
Market Trajectory and the Imperative for Updated Intelligence
Resilience, Recalibration, and Forecast Confidence
The historical period from 2020 to 2025 reveals a market that has weathered macroeconomic pressure while steadily rebuilding volume. Initial contraction phases were followed by a pronounced rebound, driven by renewed investment in coatings, automotive surface finishing, and plastic manufacturing quality programs. The post-pandemic recovery phase did not simply restore prior levels; it elevated the baseline by embedding gloss measurement more deeply into standardized production protocols. By the final year of the historical window, the market had stabilized and begun a sustained climb, setting the foundation for the current forecast period.
Looking forward, the 2026 to 2032 projection reflects a market that is structurally sound and increasingly sophisticated. Growth is anticipated to accelerate modestly in the outer years of the forecast, suggesting that adoption curves are steepening as industries recognize the cost-of-poor-quality implications of inconsistent gloss measurement. However, raw size figures tell only part of the story. The strategic narrative lies in the margin between standard compliance and advanced performance, between entry-level measurement tools and integrated systems that feed real-time data into digital quality ecosystems. The full report dissects these layers in detail, identifying the operational drivers that will separate growth leaders from laggards.
Readers of the full study will find a carefully constructed time-series analysis that reconciles historical volatility with forward-looking indicators. The research does not rely on aggregate projections alone; it triangulates demand signals across multiple industrial touchpoints, ensuring that forecasts are anchored in observable procurement behavior, standard adoption rates, and maintenance cycle dynamics. For executives planning multi-year equipment cycles or evaluating supplier partnerships, this temporal depth provides the confidence required to commit resources without overreliance on single-point estimates.
The Operational Backbone: Standards, Calibration, and Compliance
Why Governance Shapes Competitive Positioning in Gloss Measurement
Technical performance in gloss measurement cannot be separated from the regulatory and procedural frameworks that govern it. ISO 2813 remains the active standard specifying three geometries at 20, 60, and 85 degrees, alongside calibration procedures for coatings gloss measurement. ASTM D523 continues to serve as the primary test method for specular gloss of nonmetallic specimens, reinforcing the geometries and measurement protocols that define instrument credibility. These standards are not static background documents; they actively shape product development roadmaps, influence procurement specifications, and set the bar for market entry. Manufacturers that align their engineering and validation processes with these requirements secure a defensible position in customer evaluations and regulatory audits.
Beyond the standards themselves, the ecosystem of calibration and traceability introduces a critical operational layer. ISO 17025 accredited calibration services are required for glossmeter traceability and quality system compliance, meaning that long-term instrument value is heavily dependent on service infrastructure as much as hardware capability. Regular professional calibration using certified black glass standards ensures measurement accuracy in coatings and paint industries, and it maintains reliable gloss data across multiple instruments over time. This is not merely a maintenance task; it is a recurring cost and a quality risk vector that procurement teams must factor into total cost of ownership assessments. The interplay between instrument precision, calibration cadence, and documentation integrity increasingly differentiates suppliers in competitive bidding environments.
The research report situates these dynamics within a broader operational context, examining how calibration requirements influence purchasing behavior, service contract penetration, and the relocation of decision-making toward quality assurance departments with stronger compliance mandates. The full study details how these factors affect vendor selection criteria, replacement cycles, and the strategic importance of regional service networks. By illuminating these operational realities, the report provides a framework for evaluating not just the sticker price of instrumentation but the durability of the measurement capability it supports.
Application Footprints and the Multi-Industry Demand Signal
Where Surface Finish Drives Technical and Commercial Outcomes
Gloss measurement serves as a cross-industry quality indicator, but its commercial weight varies significantly by vertical. Automotive applications have established a strong demand profile, reflecting the sector's emphasis on aesthetic consistency, paint durability, and finishing precision across body panels and component surfaces. Paint and coatings represent another substantial application base, where gloss measurement functions as both a quality control gate and a formulation validation tool. The plastics sector, paper and packaging, and electronics each contribute additional demand threads, albeit with different measurement priorities and tolerance thresholds.
The strategic insight for market participants lies not in recognizing that these segments exist, but in understanding the intensity of measurement integration, the sensitivity of purchasing cycles to regulatory or standard updates, and the willingness of end-users to invest in higher-geometry or multi-angle instruments for nuanced surface characterization. Single-angle devices capture baseline gloss quickly, but two-angle and multi-angle configurations address more complex surface behaviors such as haze, distinctness of image, and directional reflectance variation. The balance among these instrument types reflects a market that is gradually moving from minimal compliance toward enriched surface analytics in select high-value applications.
The full research publication maps these application-linked demand drivers with operational granularity, connecting procurement patterns to process requirements, standard obligations, and production volumes. While the aggregate market is shaped by broad industrial activity, the real differentiation occurs in segment-specific adoption curves and the timing of technology upgrades. Decision-makers who understand these dynamics can anticipate where demand will concentrate, how specification changes will affect instrument requirements, and which application clusters will provide the most addressable growth over the forecast horizon.
Competitive Landscape and the Battle for Capability Leadership
Incumbents, Regional Challengers, and the New Features Race
The competitive field in glossmeters is defined by a mix of established specialty instrument manufacturers and regionally anchored suppliers expanding their feature sets and distribution reach. Leading players have built reputations on engineering rigor, specification alignment with ISO and ASTM requirements, and service ecosystems that support long-term measurement integrity. These incumbents often compete on precision, calibration support, and instrument longevity, positioning their products as investments in repeatable quality rather than one-time purchases. Their product portfolios span single-angle, two-angle, and multi-angle configurations, with many offering integrated haze measurement, Bluetooth connectivity, and benchtop or portable form factors tailored to laboratory, production-floor, and field inspection needs.
Alongside these established firms, a set of agile competitors from Asia and other regions has expanded the market's accessibility, offering digital glossmeters, multi-angle instruments compliant with ASTM and ISO standards, and compact units targeting cost-sensitive segments and localized service expectations. Recent developments illustrate how competitive energy is translating into market-facing activity. Activity through major exhibitions has showcased intelligent gloss meters alongside appearance measurement tools, signaling a push toward smarter instrumentation and broader metrology portfolios. Product launches have introduced new tri-angle models aligned with ASTM D523 and ISO standards, reinforcing the importance of standard-compliant hardware in maintaining credibility with regulated end-users.
The competitive narrative is therefore not simply about who holds the largest share, but about who can deliver the most credible combination of accuracy, compliance support, connectivity, and service responsiveness. Concentration metrics suggest that the market remains moderately consolidated at the top, with a significant portion of activity attributable to a limited group of leading vendors. This structure favors incumbents with strong calibration and support networks, but it also leaves room for targeted challengers to capture share through feature innovation, regional proximity, or total-cost positioning. The complete report profiles the competitive set with detailed company assessments, highlighting product architecture, geographic presence, and the strategic signals embedded in recent launches and exhibition participation.
For procurement and strategy teams, this landscape analysis is essential for risk management. Supplier concentration can create both stability and dependency, while the emergence of new entrants can pressure pricing and feature parity. The research's competitive review provides the qualitative depth needed to evaluate whether an incumbent's roadmap aligns with a company's quality roadmap, or whether a challenger's offering introduces new flexibility without compromising measurement integrity.
Strategic Themes for 2026 Decision-Makers
As the market moves further into the forecast period, several strategic themes emerge as points of focus for executives, procurement leaders, and R&D planners. First, instrument selection is increasingly influenced by total lifecycle value, including calibration access, documentation support, and the ability to maintain measurement traceability across multiple devices and locations. Second, the differentiation between basic gloss measurement and extended appearance analytics is becoming more commercially relevant, particularly where surface quality impacts downstream customer perception or regulatory acceptance. Third, service networks and regional calibration capability are gaining importance as compliance expectations rise and quality systems demand verifiable data integrity. Fourth, the competitive field is being shaped by a combination of technical heritage and rapid feature iteration, with exhibitions and product launches serving as visible indicators of where innovation is concentrating.
These themes cut across regions and applications, but their manifestation differs by market context. Procurement strategies that worked in an era of commodity instrumentation are less effective when measurement traceability, standard alignment, and service responsiveness influence vendor evaluation as much as unit cost. The full market research unpacks these themes with supporting analysis, helping organizations map them to their own operating environments and decision calendars.
Why the Full Report Is a Decision-Critical Asset for 2026
From Macro Context to Execution-Ready Intelligence
Macro data provides orientation, but execution requires depth. PW Consulting's full Glossmeter Market research is designed to bridge that gap, delivering a structured body of analysis that connects market size, forecast trajectories, application dynamics, competitive profiles, and regulatory context into a single decision-support package. The report is built for teams that need to justify capital expenditures, evaluate supplier transitions, anticipate specification changes, and assess where to invest in measurement capability for the next planning cycle and beyond.
Inside the complete study, readers will find detailed market sizing and forecast tables that support scenario planning, a rigorous review of segmentation dynamics that clarifies where growth is concentrated without overgeneralizing across regions and applications, and company-specific profiles that translate product offerings and recent activities into competitive implications. The research also integrates standards and calibration considerations as operational variables, not background facts, so that quality leaders can align instrument selection with compliance obligations and maintenance realities. Exhibition participation, product launches, and the broader innovation cadence are examined as signals of where competitive energy is heading, helping organizations separate marketing noise from meaningful capability gains.
The emphasis throughout is on actionable interpretation rather than raw enumeration. Where summary data can indicate direction, the full report supplies the connective tissue that explains why a trend matters, how it interacts with procurement cycles, and what it implies for supplier evaluation, budgeting, and roadmap planning. This is the difference between knowing the market is expanding and knowing how to position a business to capture value from that expansion.
Next Steps for Stakeholders Seeking Complete Market Intelligence
The overview presented here establishes the strategic importance of the glossmeter market for 2026 and the years that follow, but it intentionally leaves the most granular intelligence for the full research publication. Detailed segmentation values, region-specific demand structures, application-level nuance, and complete competitive profiling are reserved for the comprehensive report so that decision-makers can evaluate them in the proper analytical context. Accessing the full study will provide the level of specificity needed to validate assumptions, benchmark supplier options, and align quality investment with market trajectory.
For teams responsible for testing equipment strategy, quality system planning, or industrial market analysis, the complete report offers a foundation for confident action. The macro indicators, regulatory dynamics, competitive signals, and operational considerations described in the full research combine to form a decision framework that is practical, current, and oriented toward the realities of the 2026 to 2032 period. In a market where measurement credibility, compliance alignment, and service reliability increasingly determine purchasing outcomes, having complete and current intelligence is not optional; it is a prerequisite for strategic clarity.
For detailed analysis of this topic, please visit the official page: Glossmeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Cylinder Oil Market Hits $265M in 2025, Projected 2.6% CAGR to 2032
By PW Consulting, 2026-09-07
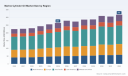
Navigating the Marine Cylinder Oil Market: Strategic Intelligence for 2026 and Beyond
Executive Summary: The Strategic Imperative
The marine cylinder oil market stands at a critical inflection point as the global maritime industry accelerates its transition toward decarbonization while balancing operational efficiency and regulatory compliance. For shipowners, operators, lubricant suppliers, and maritime service providers, understanding the nuanced dynamics of this specialized market is no longer optional—it is a strategic necessity. PW Consulting's comprehensive Marine Cylinder Oil Market research report delivers the actionable intelligence required to navigate this complex landscape through 2032.
Neurosurgery Exteroscope Market
Based on rigorous analysis spanning historical data from 2020 through 2025 and forward-looking projections extending to 2032, this report provides a granular examination of market trajectories, competitive positioning, regulatory impacts, and technological advancements that will shape decision-making in the coming years. The research equips stakeholders with the foundational knowledge needed to formulate robust procurement strategies, evaluate supplier partnerships, and anticipate shifts in market demand driven by evolving engine technologies and environmental mandates.
Backwash Laminated Filter Market
The global marine cylinder oil market has demonstrated resilient growth over the past half-decade, with revenue expanding from 225.0 million USD in 2020 to 265.0 million USD in 2025. Looking ahead, the market is projected to reach 279.07 million USD in 2026, reflecting continued demand underpinned by active shipping fleets and ongoing engine maintenance requirements. The forecast period through 2032 anticipates further expansion toward 318.0 million USD, with a compound annual growth rate of 2.6 percent. This moderate yet steady growth trajectory underscores the essential role of cylinder oils in marine engine protection, even as alternative fuels and lubrication technologies emerge.
Exoscope System Market
Market Structure and Segmentation Analysis
A deep understanding of market segmentation is vital for identifying growth pockets, assessing competitive intensity, and allocating resources effectively. Our research dissects the marine cylinder oil market across multiple dimensions, revealing the structural forces that drive demand and shape supplier strategies.
Product Type Dynamics: High-BN versus Low-BN
The cylinder oil market is fundamentally divided by alkalinity levels, measured by Base Number (BN) ratings, which determine the lubricant's capacity to neutralize acidic combustion byproducts. High-BN cylinder oils have historically dominated applications involving high-sulfur fuels, providing critical protection against acid corrosion and scuffing in two-stroke marine engines. Low-BN variants cater to operations utilizing low-sulfur fuels, where reduced alkalinity requirements align with cleaner combustion conditions and different engine wear profiles.
The balance between these product categories continues to evolve as fuel sulfur regulations reshape operational practices across global shipping routes. Engine manufacturers have responded with updated validation protocols that accommodate both traditional and alternative fuel configurations, requiring lubricant suppliers to maintain diversified product portfolios. Our report provides detailed analysis of how these category dynamics influence procurement decisions, inventory planning, and formulation development strategies.
Application Segmentation: Deep Sea and Inland Coastal Operations
Marine cylinder oil demand varies significantly according to vessel operating environments and engine duty cycles. Deep sea applications, which encompass ocean-going vessels operating on longer voyages with sustained engine loads, represent the larger segment of total market consumption. Inland and coastal operations, including short-sea shipping, harbour crafts, and regional transport vessels, constitute the complementary segment with distinct lubrication requirements driven by varying load patterns, fuel turnover rates, and maintenance intervals.
Understanding the consumption patterns across these application categories enables more precise forecasting and targeted market entry strategies. The report examines how operational profiles, engine manufacturer specifications, and voyage characteristics interact to determine cylinder oil consumption rates and replacement frequencies, providing a framework for sector-specific analysis.
Geographic Distribution and Regional Characteristics
Global demand for marine cylinder oils reflects the distribution of maritime traffic, fleet compositions, and regional regulatory environments. Different geographic markets exhibit varying preferences for product types, supplier relationships, and procurement mechanisms shaped by local operating conditions and supply chain infrastructure.
The research explores regional market characteristics without losing sight of the interconnected nature of global shipping operations. Factors such as port infrastructure, fuel availability, compliance enforcement intensity, and the presence of local blending or distribution capabilities all influence regional market dynamics. By examining these geographic nuances, stakeholders can better assess market opportunities, evaluate competitive threats, and develop regionally appropriate commercial strategies.
Competitive Landscape: Major Players and Strategic Positioning
The marine cylinder oil market features a concentrated competitive landscape where established lubricant giants and specialized regional suppliers compete on product performance, engine validation credentials, and commercial terms. Market concentration metrics indicate that a small group of leading companies commands substantial market share, reflecting the importance of engine manufacturer validations, brand reputation, and global supply chain reach in this sector.
Several major multinational energy and lubricant companies maintain prominent positions in the marine cylinder oil space, each offering validated product portfolios designed to meet the specifications of leading engine manufacturers such as MAN and WinGD. These players have invested heavily in product development to ensure compatibility with both conventional diesel and alternative fuel configurations, including LNG-capable formulations. Their cylinder oil ranges span multiple BN ratings and viscosity grades, addressing the diverse requirements of contemporary two-stroke marine engines.
Geographically diverse suppliers also play important roles in the market. European, American, Asian, and Middle Eastern companies each contribute distinct value propositions, whether through extensive global distribution networks, specialized regional expertise, competitive pricing structures, or focused product development programs. The presence of multiple validated suppliers for specific engine platforms provides vessel operators with sourcing flexibility while simultaneously intensifying competition on technical performance and commercial pricing.
Recent Developments and Regulatory Dynamics
The regulatory landscape governing marine fuels and lubricants continues to evolve, creating both challenges and opportunities for cylinder oil manufacturers and users. Recent regulatory updates and industry standardization efforts have introduced new performance requirements that directly affect cylinder oil formulation and validation processes.
The ISO 8217:2024 marine fuel standard update introduced revised fuel specifications that carry downstream implications for cylinder oil performance expectations. As fuel sulfur content specifications and other quality parameters shift, engine manufacturers and lubricant developers must ensure that cylinder oils maintain adequate protection across the range of permissible fuel qualities. These regulatory changes reinforce the importance of using validated lubricants that have been tested against current fuel specifications.
Validation protocols from engine manufacturers represent a critical gatekeeping mechanism in the marine cylinder oil market. The January 2026 publication of Version 18 of validated engine oils for WinGD engines marked a significant update, adding new products to the approved list and expanding the portfolio of cylinder oils recognized for LNG and ammonia compatibility. This validation update included several new entries alongside established products, signaling ongoing expansion in the range of approved lubricants that can support dual-fuel engine operations. Such validation milestones serve as important reference points for procurement teams seeking to ensure compliance with engine warranty and performance requirements.
Further reinforcing the technical evolution of cylinder oils, recent industry documentation has highlighted shifts in sulfur content ranges for residual fuels used in two-stroke marine engines. Validated oils for engines operating above certain sulfur thresholds now reflect adjusted formulations aligned with narrower sulfur content bands in the 1.50 to 2.50 percent range, moving away from the higher sulfur contexts historically encountered. These adjustments demonstrate the ongoing alignment between fuel quality trends and lubricant performance specifications.
New LNG-validated cylinder oils have entered the recognized product landscape, with formulations specifically designed to optimize piston cleanliness when engines operate in gas mode. These specialized products address the distinct lubrication challenges associated with gaseous fuel combustion, where different deposit formation mechanisms and wear patterns require tailored additive packages and base oil selections. The availability of LNG-validated options expands the operational flexibility of dual-fuel vessels and supports the broader transition toward lower-carbon fuel pathways.
Technological Advancements and Product Innovation
Product innovation in the marine cylinder oil sector remains active, driven by the need to protect increasingly advanced engine designs while accommodating alternative fuel combustion characteristics. Manufacturers continue to refine formulations through research and development programs focused on enhanced wear protection, improved deposit control, and extended drain intervals.
Catalog releases and formulation updates from lubricant suppliers reflect ongoing investment in product refinement. Recent updates have introduced new grades targeting medium-speed and low-speed engine applications, incorporating revised additive technologies and base oil blends designed to meet evolving performance benchmarks. These developments underscore the continuous nature of product improvement in this sector, where competitive differentiation often hinges on measurable performance advantages in engine trials and operational validation.
Engine manufacturer certifications and validations serve as crucial indicators of product credibility. Recent certification activities have confirmed the continued validity of high-BN grades for low-speed diesel crosshead engines, reinforcing the relevance of established product categories even as alternative fuel-compatible options expand. Such validations provide assurance to vessel operators that cylinder oils meeting recognized engine specifications will deliver reliable protection under designated operating conditions.
Strategic Considerations for 2026 Decision-Making
As stakeholders evaluate their positions heading into 2026 and beyond, several strategic considerations emerge from the market intelligence synthesized in this report. These themes provide a framework for aligning commercial and operational strategies with market realities.
- Engine Validation and Compliance Assurance: The availability of validated cylinder oils from multiple suppliers provides procurement flexibility but also requires careful evaluation of product-specific credentials. Ensuring that selected cylinder oils carry current validations for the target engine types and fuel configurations is essential for maintaining warranty coverage and operational reliability. The evolving validation landscape, including periodic updates from engine manufacturers, demands ongoing monitoring to avoid procurement of products that may lack current approvals.
- Fuel Transition Planning: The gradual shift toward alternative fuels, including LNG and ammonia-capable operations, introduces new lubrication requirements that differ from traditional diesel combustion scenarios. Vessel operators and managers must assess how their fleet's fuel transition timeline aligns with cylinder oil selection, considering both immediate procurement needs and future-proofing strategies. Products validated for dual-fuel operation may offer advantages in terms of operational flexibility and future compliance readiness.
- Supplier Diversification and Risk Management: The concentrated nature of the marine cylinder oil market, with leading suppliers commanding significant share, emphasizes the value of maintaining relationships with multiple credible suppliers. Diversification strategies can mitigate supply disruption risks while also enabling price competitiveness and access to technical support. Regional suppliers may offer advantages in terms of responsiveness, local technical service, and logistics convenience for specific operational bases.
- Total Cost of Ownership Analysis: Cylinder oil procurement decisions should incorporate total cost of ownership considerations beyond unit price, including factors such as consumption rates, engine wear implications, maintenance interval impacts, and availability of suitable products across the fleet. A comprehensive evaluation framework helps identify solutions that balance immediate cost objectives with longer-term operational efficiency goals.
- Regulatory Monitoring and Adaptation: The ongoing evolution of marine fuel and lubricant standards requires sustained attention to regulatory developments. Changes in fuel specifications, emissions compliance mechanisms, and certification requirements can alter the competitive dynamics of the cylinder oil market and affect product suitability assessments. Proactive regulatory monitoring enables timely adjustments to procurement specifications and supplier evaluations.
Report Methodology and Comprehensive Coverage
This market research report is the product of a rigorous analytical methodology designed to deliver reliable, actionable insights for strategic decision-making. The research integrates historical market data, forward-looking projections, competitive assessments, and regulatory analysis to construct a comprehensive view of the marine cylinder oil market environment.
The report structure encompasses detailed market sizing and forecasts that quantify revenue trajectories across the historical period and forecast horizon. Segmentation analysis breaks down market dimensions by product type, application category, and geographic region, providing the analytical granularity needed for targeted strategic planning. Competitive profiling examines the market positions, product offerings, and strategic developments of leading companies, offering context for supplier evaluation and partnership assessment.
Beyond quantitative analysis, the report explores the qualitative dynamics shaping market evolution, including regulatory developments, technological trends, and industry initiatives that influence lubricant performance requirements and procurement practices. The integration of recent validation updates, product launches, and certification activities ensures that the analysis reflects the most current market conditions and near-term developments.
Conclusion: Empowering Informed Decision-Making
The marine cylinder oil market embodies the intersection of established industrial practices and evolving technological and regulatory demands. As shipping operations continue to adapt to environmental mandates, fuel transitions, and engine technology advancements, the role of high-performance cylinder oils remains central to engine protection and operational reliability.
PW Consulting's Marine Cylinder Oil Market research report provides the depth of analysis and breadth of coverage necessary to navigate this complex market with confidence. By combining quantitative market intelligence with qualitative strategic insights, the report enables stakeholders to make informed decisions regarding procurement, supplier selection, market entry, and investment prioritization. The detailed segmentation data, competitive assessments, and forward-looking analysis contained within the full report offer the granular information required to translate strategic understanding into actionable plans.
For organizations seeking to optimize their positioning in the marine cylinder oil market through 2032 and beyond, this research represents an essential resource. The complete report delivers the comprehensive intelligence needed to support strategic planning, risk management, and competitive advantage in a market where technical excellence, regulatory compliance, and commercial agility collectively determine success.
For detailed analysis of this topic, please visit the official page: Marine Cylinder Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vitamin B6 Market to Hit $198.5M by 2032, Growing at 8.35% CAGR
By PW Consulting, 2026-09-07
Navigating the Pyridoxine Hydrochloride Landscape: Strategic Intelligence for 2026 and Beyond
The global market for Vitamin B6 (Pyridoxine Hydrochloride) is at a pivotal inflection point. As stakeholders across pharmaceuticals, nutraceuticals, and animal nutrition reassess their supply chains and product portfolios, the imperative for granular, forward-looking intelligence has never been greater. PW Consultings latest market research offers a comprehensive navigation chart for this evolving terrain, designed specifically to empower executive decision-making throughout the 2026-2032 forecast period.
Worldwide Reusable Laparoscopic Instrument Market
This article serves as an introductory insight into the depth and strategic utility of our forthcoming report. It outlines the macroeconomic trajectory, the shifting competitive architecture, and the regulatory and operational dynamics that will define profitability and market access in the coming years. While we illuminate the structural forces at play, the precise segmentation data and proprietary forecasts remain within the full study, ensuring that our clients gain an unrivalled competitive edge upon acquisition.
Construction Building Robot Market
Macroeconomic Trajectory and Growth Foundations
Understanding the scale and momentum of the Vitamin B6 market is the first step in calibrating strategic investment. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a robust historical context before projecting forward. The market has demonstrated resilient expansion, overcoming periodic fluctuations to reach a valuation of 113.0 million USD in 2025. This figure represents the culmination of a recovery and growth phase that began in the early 2020s, setting a solid foundation for the forecast era.
Worldwide Graphic Novel Publishing Platform Market
The forward outlook is characterized by sustained momentum. We project the market to ascend to 120.72 million USD in 2026, accelerating through the latter half of the decade. By 2032, the market is anticipated to reach 198.5 million USD. This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 8.35 percent over the 2026-2032 forecast period. Such a rate signals more than incremental expansion; it indicates a structural broadening of demand drivers and the successful navigation of supply-side constraints by key market participants.
For strategic planners, these macroeconomic figures are not merely statistics; they are indicators of market maturity and opportunity density. A CAGR approaching eight and a half percent in a mature vitamin segment suggests significant innovation in application, emerging market penetration, or value-added formulations. Our report dissects the sources of this growth, enabling clients to align their capital allocation with the highest-velocity segments of the market without exposing the specific numerical breakdowns that constitute our proprietary intelligence.
Structural Segmentation and Demand Architecture
The Vitamin B6 market is not a monolith. It is a complex ecosystem defined by grade specifications, application verticals, and regional dynamics. The distribution of revenue across these dimensions reveals where value is created and where competitive intensity is highest. Our research provides a detailed mapping of these segments, offering clarity on the relative weight of feed-grade versus pharmaceutical-grade material, the dominance of animal nutrition versus dietary supplements, and the divergent growth patterns across geographic zones.
In the grade segmentation, the interplay between cost-efficiency and purity standards drives distinct market behaviors. Feed-grade material constitutes a substantial portion of volume, reflecting the scale of the global animal nutrition industry. However, the pharmaceutical and food grades command different margin structures and regulatory scrutiny. The balance between these grades influences manufacturer strategy, particularly regarding capacity allocation and regulatory compliance investments. Our report analyzes how these grade-specific dynamics are evolving in response to downstream demand shifts.
Application-wise, the market is anchored by traditional uses while simultaneously embracing new therapeutic and wellness trends. Animal nutrition remains a critical consumption pillar, driven by livestock productivity requirements and aquaculture expansion. Simultaneously, the dietary supplements and pharmaceutical sectors are witnessing innovation in formulation and delivery. The convergence of these application streams creates a diversified demand base that buffers against sector-specific volatility, though it also requires nuanced go-to-market strategies. We explore the specific application drivers that are reshaping consumption patterns, highlighting where growth is decoupling from historical norms.
Regionally, the market exhibits a multi-polar structure with distinct leadership zones. North America, Europe, and Asia Pacific represent significant revenue centers, each with unique regulatory environments, consumer behaviors, and supply chain characteristics. Latin America and the Mideast and Africa contribute emerging opportunities, often characterized by different growth triggers and entry barriers. Our geographic analysis goes beyond identifying leading regions; it evaluates the strategic implications of regional shifts, including trade flows, local manufacturing capabilities, and regulatory harmonization trends. The full report provides the detailed regional revenue context and growth comparisons that are essential for market entry and expansion planning.
Competitive Landscape and Strategic Positioning
The competitive architecture of the Vitamin B6 market is defined by a mix of global chemical and pharmaceutical giants, specialized manufacturers, and regional suppliers. Market concentration metrics indicate a moderately consolidated environment, with the top three players holding approximately 32.4 percent of the market and the top five commanding around 38.7 percent. This concentration level suggests that while scale players exert significant influence, there remains ample space for specialized competitors and niche innovators to capture value, particularly in specific grades or applications.
Several key companies illustrate the diversity of strategic approaches within the sector. BASF SE, headquartered in Ludwigshafen, Germany, maintains a comprehensive presence across nutritional, feed, and pharmaceutical applications, leveraging its integrated chemical capabilities. In 2025, BASF continued to reinforce its active role in the global vitamins and animal nutrition market through feed vitamin formulations connected to pyridoxine, underscoring the importance of feed-grade integration for large-scale producers.
dsm-firmenich, based in Basel, Switzerland, operates as a global supplier with a strong footprint in pharmaceutical, nutritional, and feed uses. A critical element of their competitive posture includes active China Drug Master Files (DMFs), which facilitate access to regulated pharmaceutical markets and highlight the strategic importance of regulatory documentation in global supply chains.
In China, a cluster of manufacturers demonstrates the regions growing capabilities in Vitamin B6 production. Jiangxi Tianxin Pharmaceutical Co., Ltd., located in Leping, manufactures Vitamin B6 as pyridoxine hydrochloride in CD grade, serving as an API, food additive, and feed additive. Huazhong Pharmaceutical Co., Ltd. is an active producer for API and related markets, while Grand Health Industrial Co., Ltd. and Huisheng Biopharmaceutical also manufacture Vitamin B6 as pyridoxine hydrochloride. Guangzhou Tosun Pharmaceutical focuses on pharmaceutical use, and Hangzhou Think Chemical Co., Ltd. acts as an active supplier. Hengdian Group further contributes to production capacity. This concentration of Chinese manufacturing capabilities influences global pricing dynamics and supply availability, making geographic sourcing strategy a critical component of procurement planning.
In India, Meenaxy Pharma Pvt. Ltd. and Freemen Nutra are key players. Meenaxy Pharma operates as a manufacturer and supplier of Pyridoxine Hydrochloride API, while Freemen Nutra produces Pyridoxine Hydrochloride for pharmaceutical and nutraceutical applications. These Indian entities add to the global supply diversity and offer alternative sourcing pathways for buyers seeking to diversify their supplier base.
In the United States, Rochem International Inc. serves as a supplier and distributor of Pyridoxine HCL for health, pharmaceutical, and nutritional markets. Basic Nutrition also operates as a supplier of Pyridoxine Hydrochloride in various forms. These distributors and suppliers play a vital role in the downstream value chain, connecting manufacturing output to end-user demand across North America.
Understanding the specific capabilities, regulatory standings, and strategic moves of these competitors is essential for benchmarking and positioning. Our report provides detailed company profiles, assessing their market share trajectories, product portfolios, and potential strategic responses. This competitive intelligence allows clients to identify white spaces, anticipate competitor actions, and refine their own value propositions.
Regulatory and Operational Dynamics Shaping the Market
The Vitamin B6 market does not operate in a vacuum. Recent regulatory developments and operational realities are introducing new variables that demand strategic attention. These dynamics affect everything from product labeling and market access to manufacturing costs and margin sustainability.
Regulatory scrutiny is intensifying in key jurisdictions. In June 2025, the Therapeutic Goods Administration (TGA) in Australia issued an interim decision to amend the Poisons Standard for pyridoxine, pyridoxal, or pyridoxamine. The proposal introduces a new Schedule 3 entry for therapeutic preparations containing 50 to 200 mg per recommended daily dose. This move addresses inconsistent labeling and high-dose use, with a TGA report noting that over 1,500 ARTG listings contain vitamin B6, with nearly 80 percent providing doses above the recommended daily intake. Such regulatory actions have direct implications for product formulation, labeling compliance, and market communication strategies in affected regions.
Concurrently, the U.S. Food and Drug Administration (FDA) issued a drug safety communication in March 2026 requiring a warning label for all carbidopa/levodopa drugs regarding vitamin B6 deficiency and associated seizures. The directive mandates the evaluation of baseline levels and supplementation. This regulatory requirement highlights the clinical importance of Vitamin B6 status in Parkinson's disease management and may influence prescribing patterns, supplementation recommendations, and the development of co-formulated therapies. It also underscores the need for manufacturers and distributors to stay abreast of regulatory updates that can alter demand signals within the pharmaceutical segment.
On the operational side, the chemical synthesis of pyridoxine involves multi-step reactions utilizing volatile raw materials, including 3-hydroxy-4-methyl pyridine precursors. The price volatility of these precursors directly compresses manufacturer margins. Furthermore, price-volatile precursors and regulatory compliance costs restrict market penetration for higher-per-unit production forms of pyridoxine hydrochloride. These cost dynamics create a barrier to entry for less efficient producers and incentivize operational excellence and supply chain resilience among incumbents. Our report examines how these cost structures are evolving and what they mean for pricing power, negotiation leverage, and long-term profitability.
Innovation and Product Development Signals
Innovation within the Vitamin B6 market is manifesting through product launches that leverage the vitamin's properties in novel therapeutic and wellness contexts. These developments signal shifting consumer and clinical interests, creating new avenues for value creation.
In March 2025, Victory Select launched a cutting-edge GLP-1 and Vitamin B6 weight loss medication in Texas, shipped directly to patients' homes. This launch exemplifies the convergence of metabolic health trends with vitamin supplementation, potentially opening a new niche for combination therapies. It also reflects a direct-to-consumer distribution model that bypasses traditional pharmacy channels, a trend that may influence market access strategies for other players.
In December 2023, with a commercial launch update in 2025, Akums Drugs & Pharmaceuticals Ltd. launched Doxylamine + Pyridoxine Hydrochloride extended-release tablets. This product received approval from the CDSCO in India and the FDA, marking a significant regulatory milestone. The extended-release formulation addresses specific therapeutic needs, likely related to nausea and vomiting management, and demonstrates the potential for differentiated product features to capture market share. The dual approval underscores the global nature of regulatory strategy for innovative Vitamin B6 formulations.
These innovation signals are just part of the broader product development landscape. Our report tracks a wider array of launches, pipeline activities, and formulation technologies, providing clients with a comprehensive view of where industry creativity is directed. This insight is invaluable for R&D planning, partnership identification, and competitive response formulation.
Strategic Value for 2026 Decision-Making
The strategic value of this market research lies in its ability to translate complex data and trends into actionable decision support. For executives navigating the 2026 landscape, the report offers several critical utilities.
First, it provides a calibrated view of market sizing and growth that allows for realistic revenue forecasting and resource planning. By understanding the macro trajectory and the underlying segment drivers, companies can set informed targets and evaluate the potential return on investment for capacity expansion, marketing initiatives, or geographic entry.
Second, the competitive analysis enables precise benchmarking and positioning. Knowing the strengths, weaknesses, and strategic moves of key players allows a company to differentiate its offerings, anticipate competitive responses, and identify partnership or acquisition opportunities. The report's company profiles and market concentration insights serve as a foundation for strategic maneuvering.
Third, the regulatory and operational dynamics section equips stakeholders with the foresight to manage compliance risk and cost volatility. With regulatory frameworks evolving in markets like Australia and the United States, and raw material costs exerting pressure on margins, proactive adaptation is essential. The report outlines the specific regulatory changes and cost drivers, helping clients build resilient strategies that account for these headwinds and tailwinds.
Fourth, the innovation tracking component highlights emerging opportunities for product differentiation and market creation. Whether through combination therapies, novel delivery formats, or direct-to-consumer models, innovation is reshaping value capture. The report surfaces these trends, enabling clients to align their innovation pipelines with market-validated directions.
Finally, the segmentation analysis, while detailed in the full report, provides the lens through which to evaluate opportunity concentration. By understanding which grades, applications, and regions are driving growth, clients can prioritize their efforts and avoid dilution of strategic focus. The report's structure ensures that decision-makers can drill down into the areas most relevant to their specific business context.
Conclusion: Accessing the Full Intelligence Picture
The Vitamin B6 (Pyridoxine Hydrochloride) market in 2026 presents a landscape of structured growth, competitive nuance, and dynamic regulatory influence. The macro trajectory indicates a market expanding at a robust CAGR, supported by diverse demand drivers and a competitive field that balances scale with specialization. Regulatory updates are redefining market access and product expectations, while operational realities dictate the importance of cost management and supply chain agility. Innovation continues to open new avenues for value creation, particularly at the intersection of metabolic health and vitamin supplementation.
PW Consulting's comprehensive market research report captures this complexity in a format designed for executive utility. It goes beyond surface-level observations to deliver the deep segmentation data, competitive profiling, regulatory analysis, and forward-looking forecasts that are essential for winning strategies. The insights presented here are a preview of the depth awaiting clients who access the full study.
To secure the complete intelligence required for your 2026 strategic planning, we invite you to obtain the full report. The detailed data, including precise regional and application revenue breakdowns, granular company market share estimates, and extensive regulatory and innovation tracking, will provide the clarity and confidence needed to navigate this market successfully. Contact PW Consulting to request access to the Vitamin B6 (Pyridoxine Hydrochloride) Market research and empower your organization with the strategic advantage of comprehensive, actionable intelligence.
For detailed analysis of this topic, please visit the official page: Vitamin B6 (Pyridoxine Hydrochloride) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luffing Jib Tower Cranes Market to Hit $7,205.73M by 2032, CAGR 5.3%
By PW Consulting, 2026-09-07
Navigating the Skyline: Strategic Intelligence for the Luffing Jib Tower Cranes Market in 2026
The construction industry stands at a critical inflection point. As urban density increases and infrastructure projects grow in complexity, the demand for precise, safe, and efficient lifting solutions has never been more paramount. Among the various equipment categories, luffing jib tower cranes occupy a specialized yet vital niche, particularly suited for confined urban sites and high-rise developments where horizontal jib clearance is restricted. For stakeholders operating in this sector, understanding the trajectory of the Luffing Jib Tower Cranes Market is not merely an academic exercise; it is a prerequisite for strategic positioning in 2026 and beyond.
Rubber Blanket Shrinking Machine Market
PW Consulting's latest comprehensive market research provides a granular view of this evolving landscape. This article serves as an executive overview of the findings, highlighting the macroeconomic drivers, competitive dynamics, and operational challenges that define the sector. However, the true depth of this analysis—including specific regional revenue splits, detailed segmentation growth rates, and proprietary competitor benchmarking—resides within the full report. The following insights are designed to illuminate the strategic value of the data while underscoring the necessity of accessing the complete intelligence package for actionable decision-making.
Industrial Gas Blending Platforms Market
Market Trajectory and Growth Fundamentals
The historical performance of the luffing jib tower cranes market demonstrates a resilient upward trend, punctuated by periods of adjustment reflective of broader economic conditions. From 2020 to 2025, the market experienced significant expansion, driven by post-pandemic recovery efforts and sustained investment in commercial and industrial construction. The total market revenue, measured in USD Millions, has shown a consistent trajectory, moving from approximately 3,674 million in 2020 to nearly 4,989 million in 2025. This historical baseline establishes a robust foundation for the forecast period extending through 2032.
Thermally Conductive Copper Powder Market
Looking ahead, the market is projected to continue its expansion with a Compound Annual Growth Rate (CAGR) of 5.3 percent during the forecast period from 2026 to 2032. This growth rate suggests a steady maturation of the market rather than explosive volatility. By 2032, the overall revenue landscape is expected to reach significant milestones, reflecting the cumulative effect of new infrastructure spending, urbanization trends, and the replacement cycle of aging equipment. For enterprise strategists, this CAGR indicates a stable environment for capital expenditure planning, though it also implies intensifying competition for market share as the pie grows larger.
It is crucial to note that while the aggregate numbers provide a high-level view, the distribution of this growth across different regions and application types varies significantly. The full report dissects these variations to reveal where the highest value opportunities lie. For instance, while the total revenue figures are impressive, the specific contribution of different geographic zones to this total is a key variable in supply chain and sales network optimization. Access to the complete segmentation data allows companies to prioritize markets that offer the best risk-adjusted returns, rather than relying on generalized global trends.
Strategic Segmentation and Application Nuances
Understanding the market requires a deep dive into how demand is split by crane type and application. The luffing jib segment itself competes within a broader tower crane ecosystem that includes hammerhead, flat top, and self-erecting models. Each type serves distinct operational needs. Luffing jib cranes are specifically favored in scenarios where space is constrained or where lower horizontal clearance is required to avoid overflight restrictions. The revenue associated with this specific segment is a critical metric for manufacturers specializing in this technology, as it dictates R&D focus and inventory strategy.
In terms of application, the construction of high-rise buildings remains the dominant driver of demand. The vertical expansion of major metropolitan areas necessitates cranes that can lift heavy loads to significant heights while maintaining stability in windy conditions. However, infrastructure projects and other industrial applications also contribute substantively to the market volume. The interplay between these application sectors creates a diversified demand profile. For example, a slowdown in residential high-rises might be offset by a government-led push in infrastructure development.
The strategic implication for businesses is that reliance on a single application segment introduces vulnerability. The full research briefing provides a detailed breakdown of these application segments, offering insights into which sectors are showing the strongest momentum for luffing jib adoption specifically. This level of detail is essential for sales teams to tailor their pitches and for procurement officers to anticipate demand fluctuations. Without this granular view, companies risk misallocating resources to saturated segments while overlooking emerging pockets of demand.
Competitive Landscape and Key Player Dynamics
The market is characterized by a moderately concentrated competitive landscape, with top players holding a significant portion of the market share. The CR3 and CR5 metrics indicate that while there is room for niche players, the major incumbents possess substantial influence over pricing, technology standards, and supply chain logistics. Several key companies define the current state of play, each bringing distinct technological philosophies and regional strengths to the table.
Liebherr, headquartered in Switzerland, continues to set benchmarks in performance and reliability. Their HC-L and HC-LH luffing jib series are designed for construction sites requiring maximum flexibility. Recent product launches, including the new generation HC-L models unveiled at bauma 2025, emphasize enhanced performance and reduced downtime. This focus on operational efficiency resonates with large-scale contractors looking to minimize project timelines. Similarly, Manitowoc Company, based in the USA, leverages its Potain brand to address supertall building requirements. The global debut of the Potain MR 819 at bauma 2025, with up to 64 tons maximum capacity, signals a push towards higher capacity solutions. Furthermore, the launch of the MCR 505 J25 in late 2025 highlights a strategy balancing compact design with advanced monitoring systems like VISU+.
European manufacturers such as Comansa in Spain and Terex Tower Cranes in Italy maintain strong positions through specialized offerings. Comansa provides luffing series with substantial load and reach capabilities, catering to heavy-duty needs. Terex, through its Raimondi brand, focuses on control and safety. The recent launch of the CTL 712-45 at CONEXPO 2026 underscores this commitment to safety and efficiency in high-rise environments. Wolffkran in Germany offers modular luffing jib cranes in multiple versions, providing adaptability for urban construction and constrained sites.
Asian manufacturers are also increasingly influential. Zoomlion from China and XCMG offer tower crane ranges that include luffing jib models for global construction needs, often bringing competitive pricing and scalable production capabilities to the market. Meanwhile, specialized firms like Raimondi, Sáez Gruas in Spain, and Jaso in Italy contribute to the diversity of the landscape with high-end offerings and long-standing portfolios. Jaso, for instance, leverages a 50-year tower crane portfolio to sustain trust in their luffing jib models.
Strategic planning in this environment requires more than knowing who the competitors are. It demands an understanding of their recent development timelines, product launch cycles, and how these align with market demand peaks. The full report details these competitive moves, providing a timeline of recent developments that helps companies anticipate competitor saturation points and identify gaps in the market offering.
Industry Dynamics: Materials, Regulation, and Supply Chain
External factors exert profound pressure on market operations and profitability. Material costs, particularly steel, are a primary determinant of manufacturing expenses. In 2025, steel prices exhibited a stable trend with a downward bias, leading to fluctuations between 5 and 8 percent. This resulted in a decrease in overall crane costs compared with 2024. For buyers, this creates a favorable procurement environment in the short term. For manufacturers, it necessitates agile pricing strategies to maintain margins while capitalizing on reduced input costs.
However, cost advantages can be negated by supply chain disruptions. As of early 2026, sector analysis indicates that component shortages, including semiconductors and steel structures, continue to cause manufacturing delays and project slowdowns. This persistent volatility requires companies to build resilience into their supply chains, potentially through diversification of suppliers or increased inventory buffering for critical components. The interplay between raw material cost reductions and supply chain bottlenecks creates a complex operational environment that demands careful monitoring.
Regulatory frameworks are also tightening, influencing both equipment design and operational protocols. ISO standards for tower cranes mandate enhanced safety protocols for variable jib luffing systems, particularly in high-rise and urban environments. Compliance with these standards is not optional; it is a barrier to entry and a key differentiator for reputable brands. Furthermore, tower crane operator programs across various jurisdictions are increasingly incorporating training for luffing jib and articulated jib models to address rigging safety practices. This regulatory focus on human capital and operational safety adds a layer of complexity to project execution and equipment deployment.
These dynamics suggest that the winners in the 2026-2032 period will be those who can navigate the supply chain maze while maintaining strict adherence to evolving safety standards. The market research delves into these dynamics, quantifying the potential impact of regulatory changes and supply chain risks on market growth and profitability.
The Strategic Value of Comprehensive Intelligence
In an industry defined by high capital intensity and long project lifecycles, decision-making must be grounded in robust data. The overview provided here highlights the macro trends, key players, and external pressures shaping the Luffing Jib Tower Cranes Market. However, the difference between a good strategy and a great one often lies in the details that are not visible from the surface.
Access to the full market research unlocks several critical capabilities for your organization. It allows for precise identification of high-growth sub-segments without relying on assumptions. It provides the specific regional revenue data necessary to optimize distribution networks and sales targets. It offers a deeper competitive analysis that goes beyond product summaries to include market share implications and strategic positioning. Furthermore, it contextualizes the recent developments from companies like Liebherr, Manitowoc, and Raimondi within the broader timeline of market evolution, helping you anticipate the next wave of innovation.
The 5.3 percent CAGR and the projected revenue milestones through 2032 are encouraging indicators, but they do not tell the whole story. The volatility in raw materials, the nuances of regional demand, and the specific competitive maneuvers of the top ten players require a detailed playbook. PW Consulting's report is designed to be that playbook. It transforms raw data into actionable intelligence, enabling stakeholders to mitigate risk and capture opportunity in a market that is both stable in its growth trajectory and complex in its execution.
For executives, investors, and strategic planners looking to secure a competitive edge in the luffing jib tower crane sector, the comprehensive data set is an essential asset. We invite you to explore the full report to gain the specific insights required to navigate the coming years with confidence.
For detailed analysis of this topic, please visit the official page: Luffing Jib Tower Cranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com